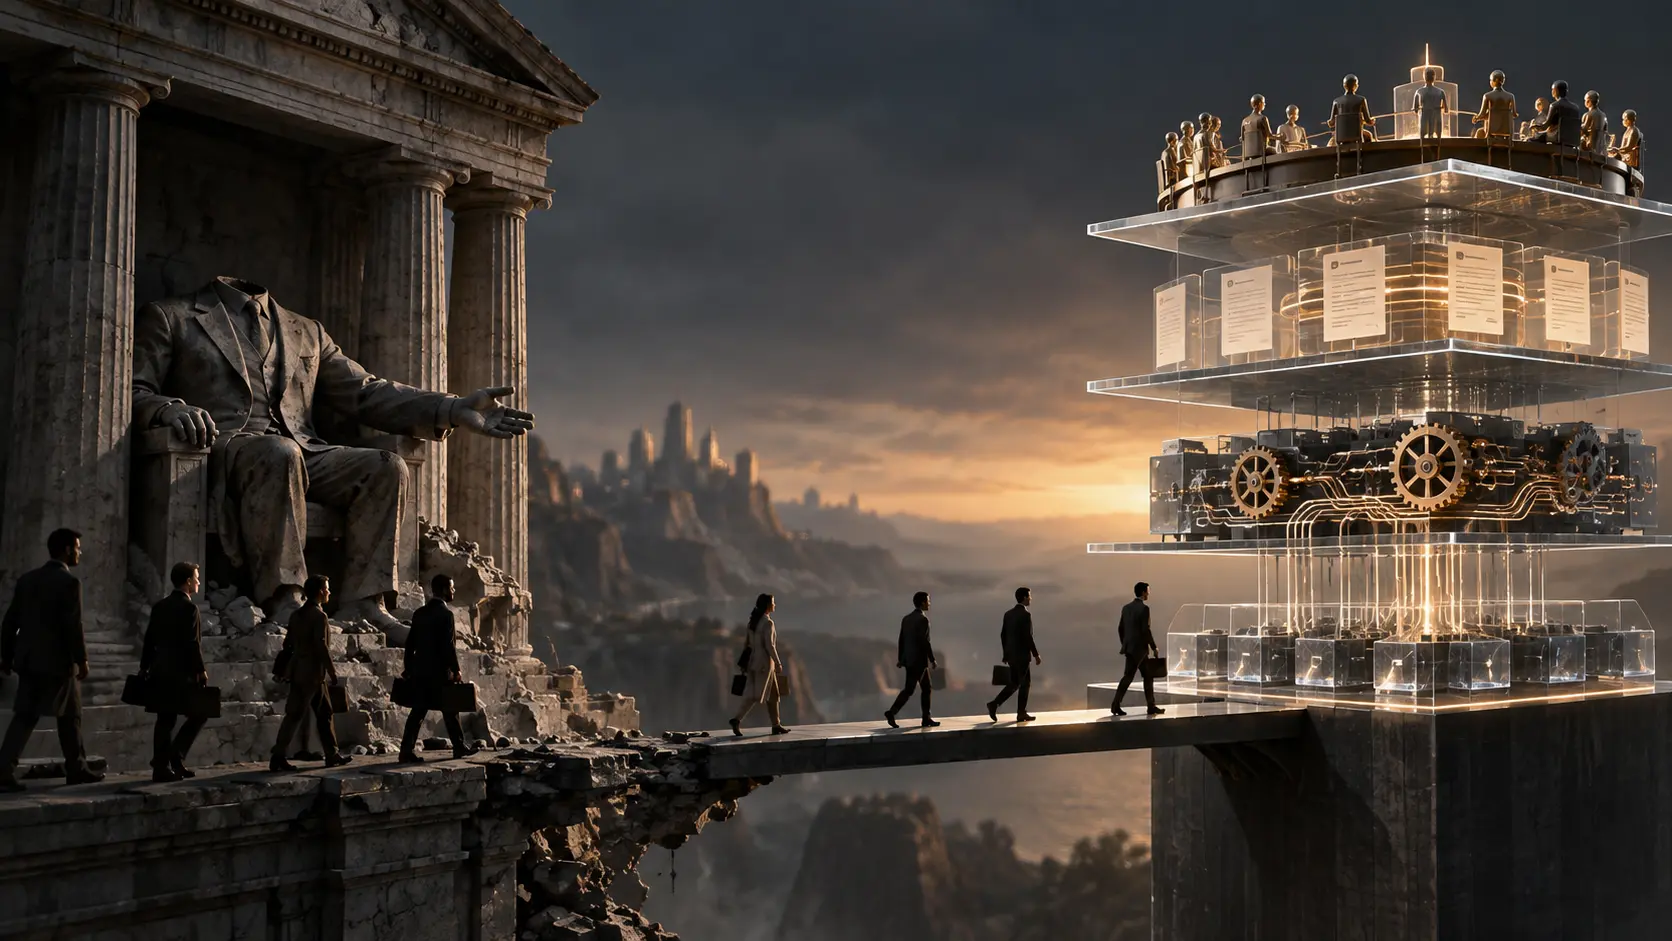
Decentralized finance is often described as an attempt to remove financial intermediaries. That description captures part of what DeFi changes, but it can also be misleading. DeFi does not make coordination, information, rule-setting, access, and risk management disappear. Instead, it redistributes many of those functions across protocols, smart contracts, oracles, developers, interfaces, governance systems, and other technical components. The traditional intermediary may disappear from one part of the transaction while new forms of intermediation emerge elsewhere.
In conventional finance, an institution often performs several functions at once. A bank may hold customer assets, maintain account records, assess collateral, execute payments, determine lending conditions, and enforce contractual rules. An exchange can custody assets, maintain an order book, match buyers and sellers, and control access to its market. Users rely on these organizations not only because they possess the necessary infrastructure, but because they coordinate activities that would otherwise be difficult for individuals to perform independently.
DeFi separates many of these functions and expresses some of them through software. A lending protocol, for example, can allow a user to deposit collateral and borrow assets according to predefined rules. Smart contracts keep track of positions, calculate certain financial conditions, and can automatically liquidate collateral when specified thresholds are reached. There may be no loan officer approving each transaction and no institution maintaining a private internal ledger. Part of the intermediary's role has been transferred to the protocol.
A decentralized exchange provides another example. Instead of sending assets to a company that operates a conventional trading venue, users can trade through smart contracts. In some designs, other participants deposit assets into liquidity pools, and mathematical rules determine how exchanges occur. The protocol performs functions that would traditionally require a market operator and supporting infrastructure. Yet this does not mean that mediation has disappeared. The mechanism coordinating the trade has changed from an organization to a combination of code, liquidity providers, blockchain infrastructure, and economic incentives.
Smart contracts therefore become a new kind of intermediary, although not an institution in the traditional sense. They sit between participants and determine what happens to assets according to programmed rules. The difference is that their behavior can often be inspected in advance and executed without individual discretion. A contract does not decide that one borrower looks trustworthy while another does not. It applies whatever conditions were encoded into the protocol.
This can reduce certain forms of dependence, but it creates others. Users must trust that the code behaves as expected, that it does not contain serious vulnerabilities, and that its economic design remains functional under stress. If a smart contract makes an error, the problem may be more difficult to correct than a mistake inside a conventional financial database. Replacing a human intermediary with software therefore changes the nature of the dependency rather than eliminating it.
Oracles illustrate this transformation particularly clearly. Many DeFi protocols need information that the blockchain cannot generate independently. A lending system may need to know the market price of collateral. A derivatives protocol may require reference prices. Smart contracts cannot simply observe external markets, so they depend on mechanisms that bring outside information onto the blockchain.
The oracle effectively performs an informational function that traditional financial institutions often handle internally or purchase from specialized data providers. If the oracle supplies an inaccurate price, an automated protocol may liquidate users incorrectly or calculate positions using distorted information. The smart contract can execute perfectly while still producing harmful results because the intermediary responsible for supplying information failed. Automation has not removed the need for trustworthy data; it has made the data layer more visible and modular.
Developers assume another function that was previously concentrated inside institutions. Someone must design the protocol, write the code, fix vulnerabilities, develop new versions, and decide which technical possibilities should be pursued. Open-source development can distribute these activities among many contributors, but in practice complex protocols often depend heavily on relatively small groups of experienced developers.
Their influence differs from that of a bank executive or exchange operator. Developers may not directly control user funds, and users may be able to inspect or reject software changes. Even so, technical expertise creates power. The people who understand a protocol deeply enough to maintain it can shape which upgrades are proposed, how security problems are addressed, and which trade-offs are embedded in future versions.
Upgradeability makes this role especially important. Some DeFi applications allow contracts to be modified after deployment. This can make it possible to repair vulnerabilities or introduce new features, but someone must control the upgrade process. The authority may belong to a development team, a multisignature committee, token holders, or another governance mechanism. Users are therefore not relying only on the current code. They are also relying on whoever can change that code.
Interfaces form another intermediary layer. Most users do not interact directly with smart contracts by constructing blockchain transactions manually. They visit websites, open applications, or use wallets that present the protocol through a familiar interface. That interface translates complex blockchain operations into buttons, menus, balances, and transaction prompts.
The underlying protocol may be permissionless, but the interface can still be operated by a company or development team. It may restrict certain users, remove access to particular functions, become unavailable, or display information incorrectly. Technically sophisticated users may be able to access the protocol through alternative interfaces or interact with the contracts directly, but for many participants the main website effectively serves as the gateway to the system.
This creates an important distinction between protocol access and practical access. A DeFi application can remain operational on the blockchain even if its primary website disappears. In that sense, it may be more resistant to the failure of a single operator than a conventional financial platform. But if most users cannot interact conveniently without that interface, centralization has reappeared at the access layer.
Governance replaces another set of institutional functions. Traditional financial companies have executives, boards, legal structures, and internal committees responsible for changing policies and allocating resources. DeFi protocols may instead use token voting, delegates, community proposals, foundations, multisignature groups, or combinations of these mechanisms.
These systems can broaden participation, but they do not automatically distribute power evenly. Token ownership may be concentrated. Many holders may not vote. Delegates can accumulate significant influence. Foundations and development organizations may control large treasuries or provide most of the technical work required to implement approved decisions. A protocol can therefore have decentralized governance in formal design while practical decision-making remains concentrated among a relatively small group.
Liquidity providers perform another function that traditional institutions often perform through market making and balance-sheet capital. In automated markets, users or professional firms can deposit assets into pools that facilitate trading. They are compensated according to the protocol's rules and the risks they assume. The market-making function becomes open to a broader set of participants, but the system still requires someone to supply capital.
If liquidity becomes concentrated among a small number of large providers, those participants can become economically important even without formal control over the protocol. Their withdrawal can make trading more expensive and markets less stable. Once again, the intermediary has not vanished; the role has been separated from the traditional institution and redistributed through a different structure.
Stablecoin issuers add another layer of dependency. Much of DeFi relies on assets designed to maintain a relatively stable value. Some of the most widely used versions are issued by centralized organizations that hold reserves and manage redemption. A lending protocol may be governed through decentralized mechanisms and executed through smart contracts while relying heavily on a stablecoin whose issuer remains a conventional company.
This creates hybrid systems in which decentralized and centralized components are deeply connected. A user may borrow through an autonomous protocol, trade through a decentralized exchange, and hold funds in a stablecoin, all within one transaction path. Yet each component has different trust assumptions. The lending protocol depends on code and governance, the exchange depends on liquidity and smart contracts, and the stablecoin may depend on an issuer, banks, reserves, and legal arrangements.
Custody can also be transformed rather than universally eliminated. DeFi allows users to retain control of their own blockchain credentials and interact with applications without depositing assets into a conventional institution. This can reduce dependence on centralized custodians. But self-custody makes wallets, private keys, transaction signing, and personal security far more important. The function of protecting access to assets moves from an institution toward software and the individual user.
That shift has consequences. A bank can sometimes reverse an unauthorized transfer or restore account access after identity verification. Blockchain transactions may be much harder to reverse, and losing control of private keys can result in permanent loss. Removing the custodian removes some risks while transferring responsibility and creating others.
Even risk management becomes partly transformed. Traditional institutions may employ teams responsible for credit analysis, collateral policies, market risk, and emergency intervention. DeFi protocols can encode some of these functions into collateral ratios, liquidation mechanisms, interest-rate formulas, and automated limits. The rules become more transparent and predictable, but they cannot anticipate every possible market condition.
When extreme volatility occurs, a protocol may discover that its assumptions about liquidity, asset correlations, or collateral quality were too optimistic. Automated liquidations can occur exactly as designed while still producing losses for the system. In such cases, the absence of a discretionary intermediary can become a trade-off rather than a simple advantage. Automation provides consistency, but consistency does not guarantee that the underlying rule is appropriate in every circumstance.
DeFi is therefore best understood as a reorganization of financial intermediation. Some roles once combined inside a single company are decomposed into separate components. Smart contracts enforce rules, oracles provide information, liquidity providers supply capital, developers maintain software, interfaces connect users to protocols, and governance systems coordinate change. Each component can be more open or more concentrated depending on its design.
This modularity can create meaningful advantages. A user may be able to choose a different interface without leaving the underlying protocol, replace one wallet with another, provide liquidity directly, or interact with financial infrastructure without opening an account with the organization that developed it. Components can sometimes be replaced independently, reducing the power of any single institution.
But modularity also means that risk can hide in the connections between components. A protocol may be secure while its oracle fails. Its contracts may work while a stablecoin loses credibility. Its governance may be distributed while the main interface becomes inaccessible. Its liquidity may appear deep until several large providers withdraw simultaneously. Evaluating DeFi therefore requires examining the entire chain of dependencies rather than focusing only on whether the smart contracts are decentralized.
The central change introduced by DeFi is not the disappearance of intermediaries but the possibility of separating their functions and placing some of them inside transparent, programmable systems. Trust can move from a bank to code, from an exchange to a liquidity protocol, from an internal price database to an oracle, and from a corporate management team to a governance mechanism. Each transition removes certain powers while introducing new points of dependence.
Whether this represents meaningful decentralization depends on how replaceable those components are and how much authority any one of them possesses. A system becomes less dependent on centralized control when users can switch providers, verify rules independently, retain custody, access alternative interfaces, and continue using the protocol when individual organizations fail. DeFi's most important contribution is therefore not a world without intermediaries, but a different architecture in which the roles intermediaries once performed can be divided, automated, inspected, and, in some cases, made easier to replace.
