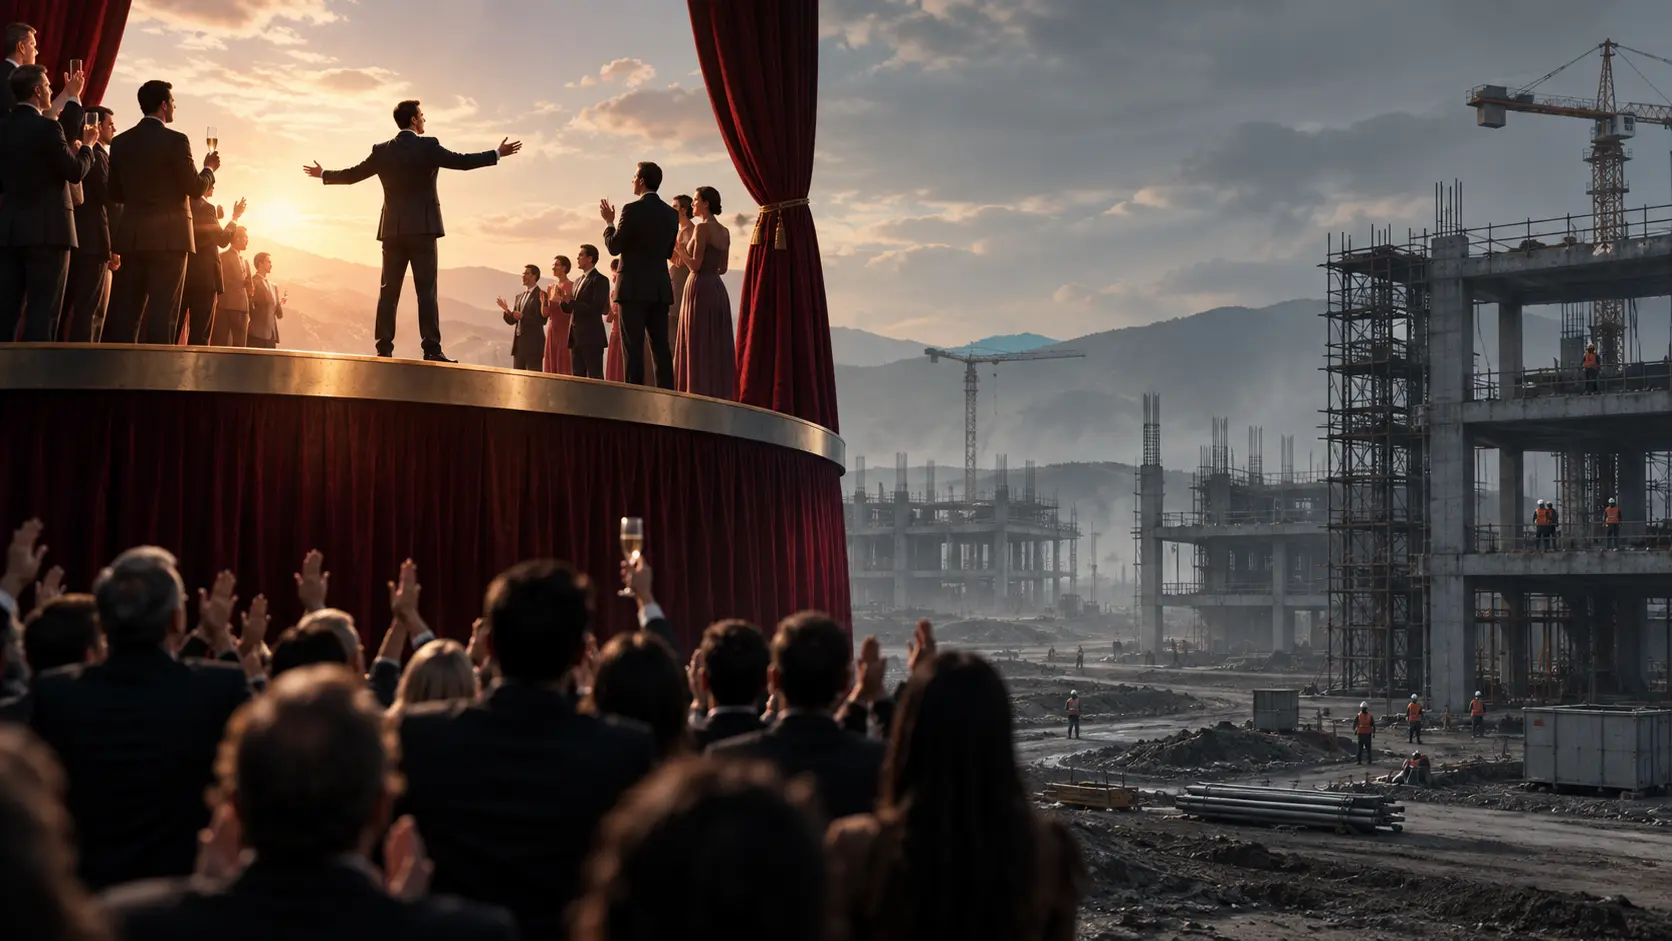
Financial markets often price the future long before that future exists. In crypto, this tendency is especially strong because many assets are valued less by what their underlying networks do today than by what investors believe they could become. A new blockchain, protocol, or technical idea may still have limited users, weak infrastructure, and uncertain economics, yet its associated asset can rise sharply if the market becomes convinced that it represents an important future trend. In these cases, expectation does not merely reflect adoption. It can run years ahead of it.
A narrative is the story investors use to explain why an asset may become more valuable. It might be built around faster blockchains, decentralized finance, tokenized real-world assets, artificial intelligence, privacy, digital ownership, or some other technological shift. The story does not need to be false to move prices prematurely. A technology can have real potential while still being far from widespread use. Markets often compress a long and uncertain development path into a much simpler belief: if this technology becomes important, the assets associated with it should be worth more.
That belief can affect prices almost immediately because capital moves much faster than technology. Investors can buy a token in seconds, while building reliable infrastructure, attracting developers, establishing standards, winning regulatory acceptance, and changing user behavior can take many years. The result is a mismatch between the speed of financial speculation and the speed of technological adoption. Prices can react to a plausible future almost instantly, even when the underlying system is still experimental.
This is not unique to crypto. Public markets have repeatedly valued companies based on expected future growth rather than current profits. What makes crypto distinctive is the degree of uncertainty and the direct link between many technologies and tradable tokens. Investors may have little historical data, few established valuation models, and limited evidence about long-term demand. In that environment, narratives become especially influential because they provide a framework for imagining future value when present fundamentals are still weak or incomplete.
Once a narrative gains momentum, it can become self-reinforcing. Rising prices attract attention, attention brings more investors, and new investment is interpreted as evidence that the thesis is gaining credibility. Developers may begin building around the trend because funding is available. Companies adopt the language of the narrative because it helps them raise capital or attract users. Media coverage increases, social discussion expands, and related tokens are grouped into a common category. The market begins to behave as though adoption is already underway, even when practical use remains modest.
This process can sometimes help make the narrative more real. Higher valuations can finance development, encourage experimentation, and draw skilled people into the sector. A technology that initially attracted speculative capital may eventually benefit from the resources created by that speculation. In this sense, expectations can influence outcomes. Investors do not merely predict the future; by directing money and attention toward a technology, they can help create some of the conditions required for it to develop.
The difficulty is that financial enthusiasm can reach maturity long before the technology does. Early products may be expensive, difficult to use, unreliable, or unnecessary for most people. Developers may face technical problems that take years to solve. Businesses may not yet have a strong reason to adopt the system. Regulation may remain unclear, and users may prefer familiar alternatives. None of these obstacles necessarily invalidate the long-term idea, but they can make near-term expectations unrealistic.
This creates an important distinction between technological potential and investment timing. A technology can eventually become useful without justifying every valuation attached to it during its early years. Investors may correctly identify a major trend and still overpay for assets associated with it. Markets can be right about the direction of change but wrong about how quickly that change will happen, which projects will dominate, and how much economic value will ultimately flow to particular tokens.
Time is especially important because adoption rarely happens in a straight line. New technologies often require several layers of development before they become broadly useful. Basic infrastructure must work reliably. Tools for developers must improve. Interfaces need to become simple enough for ordinary users. Businesses need economic incentives to integrate the technology. Legal and operational uncertainty must decline. Each stage can take longer than expected, and progress in one area does not guarantee progress in another.
Narratives tend to hide this complexity. A broad phrase such as “tokenization will transform finance” can be directionally plausible while leaving unanswered questions about custody, regulation, settlement, liquidity, interoperability, and actual demand. Similarly, a claim that a new blockchain will support mass adoption says little about whether users need its applications, whether developers will build on it, or whether the token itself will capture value from that activity. The story may be compelling because it simplifies a difficult future into an investable idea.
That simplification is powerful during bull markets. When investors are willing to take risk, they often reward distant possibilities because immediate evidence seems less important. Assets linked to a fashionable narrative can rise together even when the quality of the underlying projects differs sharply. The category itself becomes investable. Once market conditions weaken, however, investors often demand proof that was previously considered unnecessary. Usage, revenue, developer activity, product quality, and economic sustainability suddenly matter much more.
This helps explain why prices can collapse even when the underlying technology continues to improve. A falling token does not always mean the idea has failed. It may mean that expectations had advanced much faster than reality. The technology can continue progressing while the market spends years adjusting from an overly optimistic valuation. Conversely, renewed technological progress does not guarantee an immediate price recovery if investors have already lost confidence in the narrative.
Another source of uncertainty is that the eventual winners may not be the projects that first popularized the idea. Early enthusiasm often focuses on pioneers because they are visible when a new category emerges. But later competitors may build better products, adopt stronger economic models, or benefit from improved infrastructure. A correct narrative about an industry can therefore coexist with incorrect assumptions about which specific asset will capture the value created by that industry.
Investors also face the problem of value capture. A network can become widely used without its token necessarily appreciating in proportion to that use. The relationship depends on how fees work, how tokens are issued, whether users must hold them, how supply changes over time, and whether economic activity actually creates persistent demand for the asset. Technological adoption and token value are related in some systems, but they are not interchangeable concepts.
For this reason, narratives are most useful when treated as hypotheses rather than conclusions. A strong story can identify an area worth studying, but it cannot substitute for evidence about whether adoption is occurring and whether a particular asset benefits from it. The more distant the promised future, the more uncertainty exists between the narrative and the eventual outcome. Technical execution, competition, regulation, user behavior, and market structure can all change during that period.
Crypto markets repeatedly show how powerful future expectations can be. Prices can move long before networks achieve meaningful scale because investors are constantly trying to anticipate what others will value later. Sometimes that anticipation helps accelerate genuine progress. Sometimes it creates valuations that reality cannot support. The central tension is that markets are built to discount the future, while technology is built through slow, uneven work in the present. Understanding that difference is essential for separating a promising technological direction from an investment thesis whose timing and valuation may already assume too much.
