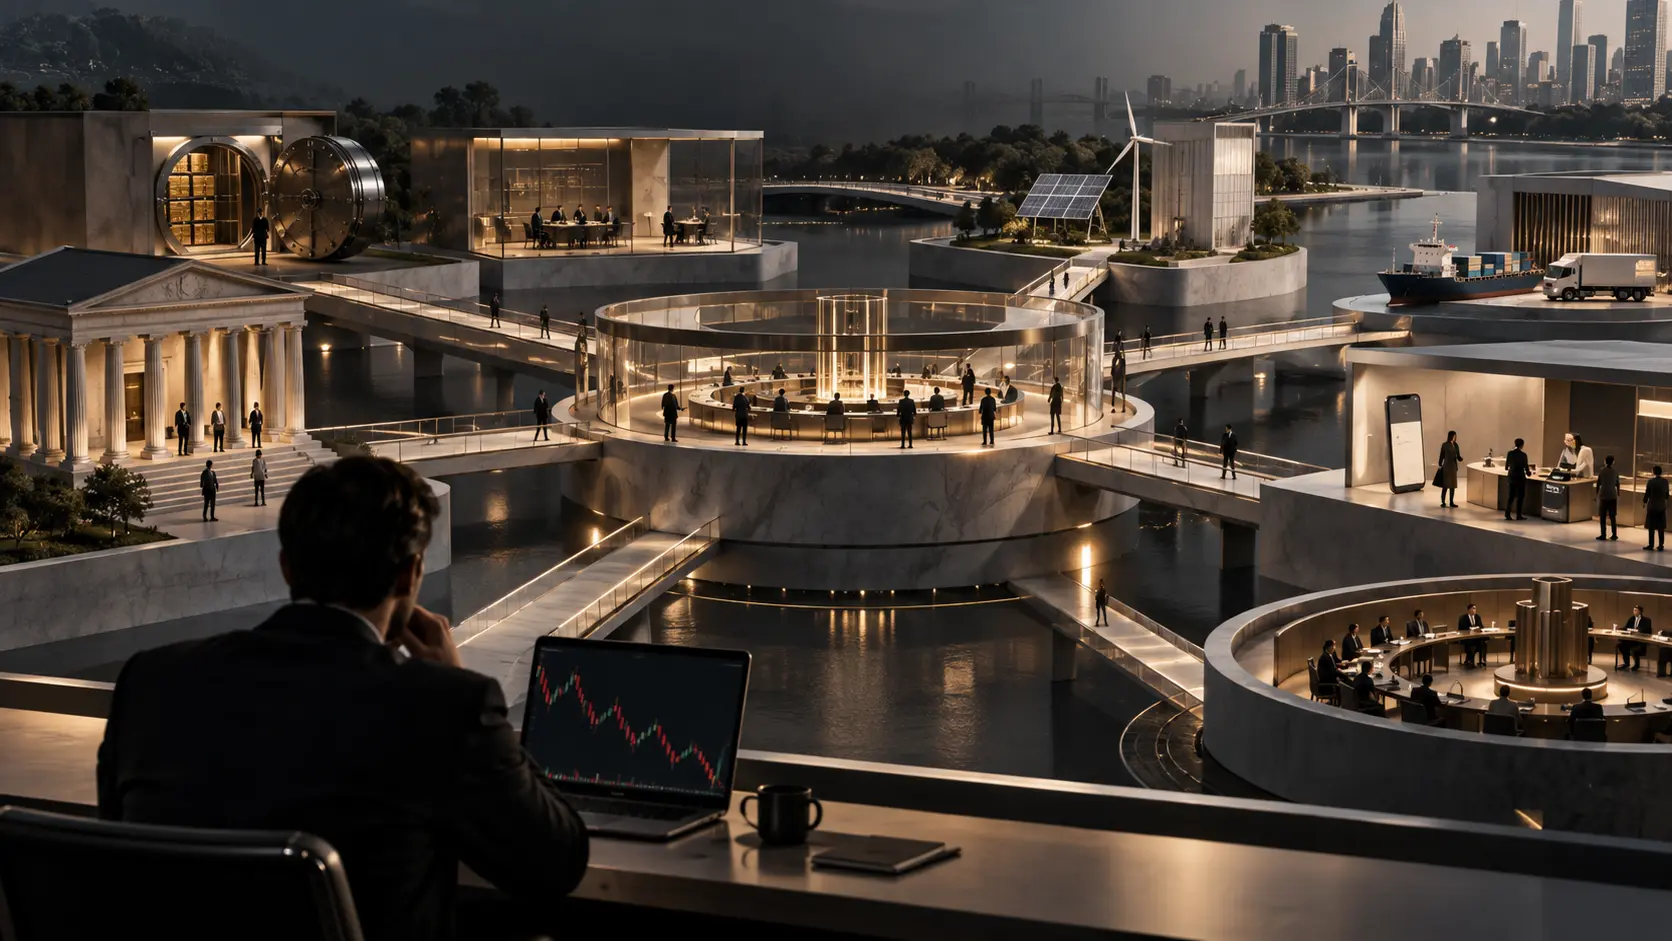
For many people, the crypto market is reduced to a screen full of prices. Bitcoin rises, Ether falls, a smaller token gains 20% in a day, and the conversation quickly becomes a debate about whether the market is bullish or bearish. Prices matter, but they show only the most visible layer of a much larger system. Behind every quotation is an expanding network of blockchains, financial protocols, stablecoins, tokenized assets, trading venues, custody services, payment systems, data providers, and technical infrastructure. Looking only at prices is a little like judging the internet solely by the stock prices of technology companies: useful for understanding market sentiment, but far from enough to understand what is actually being built and used.
Cryptocurrencies are the easiest part of the ecosystem to observe because their prices are public, continuous, and highly volatile. Bitcoin, Ether, and thousands of other digital assets trade around the clock, creating an endless stream of market data. This visibility naturally attracts attention. Price movements are easy to measure, compare, and discuss, while the development of a payment network, lending protocol, custody system, or tokenization platform is slower and less dramatic. As a result, public perception often confuses the performance of crypto assets with the progress of the crypto industry itself.
The first layer beneath prices is the blockchain network. A blockchain is not simply a place where a coin exists. It is a shared digital infrastructure that allows participants to record transactions, transfer assets, and run applications according to predefined rules. Different networks are designed with different priorities, such as security, transaction speed, programmability, privacy, or low operating costs. Bitcoin is primarily associated with transferring and holding a scarce digital asset, while programmable networks such as Ethereum support applications that can execute financial agreements automatically through software known as smart contracts. Other blockchains compete or specialize in areas such as payments, trading, gaming, digital identity, and institutional financial infrastructure.
The health of these networks cannot be understood by price alone. Activity can also be examined through transaction volumes, fees, active addresses, developer participation, validator economics, computing resources, and the amount of capital committed to applications. None of these measures is perfect, and they can sometimes be distorted, but together they reveal whether a network is being used and what kinds of economic activity are taking place on it. A token may rise sharply in price despite limited practical use, while another network may experience growing adoption even during a period of weak market prices.
Built on top of blockchain networks are protocols, which function somewhat like financial applications with rules embedded in software. Decentralized finance, commonly called DeFi, is one of the clearest examples. DeFi protocols allow users to exchange assets, provide liquidity, borrow, lend, issue derivatives, or earn returns without relying on the same centralized structure used by a traditional bank or brokerage. Instead, transactions can be coordinated through smart contracts. This does not eliminate risk or intermediaries entirely. Software developers, governance systems, price-data providers, liquidity providers, wallet companies, and blockchain operators can all play important roles. What changes is the architecture through which the financial service is delivered.
Decentralized exchanges illustrate this difference. On a conventional cryptocurrency exchange, the company generally operates the trading platform and controls much of the transaction process. On a decentralized exchange, users can trade directly through smart contracts, often while retaining control of their assets in their own wallets. Liquidity may be supplied by other users rather than by a traditional market-making structure. These systems create new possibilities, but they also introduce risks involving software flaws, poorly designed incentives, market manipulation, and illiquid assets. Understanding the crypto market therefore requires studying how these protocols work, not simply whether the tokens associated with them are rising or falling.
Stablecoins have become another central part of the ecosystem. Unlike highly volatile cryptocurrencies, stablecoins are designed to maintain a relatively stable value, usually by tracking a national currency such as the U.S. dollar. Their importance comes less from speculative price appreciation and more from their function. They allow value to move between exchanges, wallets, protocols, businesses, and users without requiring every transaction to pass directly through the traditional banking system. In markets where access to dollars is limited or banking services are expensive, stablecoins can also serve as a digital representation of a widely used foreign currency.
Not all stablecoins work in the same way. Some are backed by reserves such as cash and short-term government securities held by an issuing company. Others depend on crypto collateral or algorithmic mechanisms. Their structures create different kinds of risk, including reserve risk, redemption risk, regulatory exposure, and technical failure. The collapse of poorly designed stablecoin systems has shown that maintaining a stable price is not simply a matter of naming an asset after a currency. The quality, transparency, and liquidity of the mechanism supporting the token matter greatly. Stablecoins therefore represent a financial market of their own, with questions involving payments, banking, monetary policy, regulation, and cross-border capital flows.
Tokenization extends the crypto model beyond native digital assets. In simple terms, tokenization involves representing ownership or rights to an asset on a blockchain. The underlying asset may be a government bond, a fund share, a commodity, real estate interest, private credit instrument, or another financial claim. The purpose is not necessarily to create a new speculative cryptocurrency. In many cases, the goal is to improve settlement, automate administrative processes, increase transparency, or make financial instruments easier to transfer and integrate with programmable systems.
This is one of the areas where the boundary between traditional finance and crypto becomes increasingly difficult to define. A tokenized Treasury security, for example, may be issued by a regulated financial institution, backed by conventional assets, held by investors through digital wallets, and transferred over blockchain infrastructure. The investment exposure remains familiar, but the rails used to issue, record, and transfer the asset are different. The same logic can apply to funds, debt instruments, and other securities. As tokenization develops, some of the most important crypto-related activity may involve assets whose economic value comes from outside the crypto market.
Infrastructure is another largely invisible part of the industry. Users see wallets, exchanges, and applications, but these products depend on a deeper technical stack. Blockchains require validators, miners, or other mechanisms to confirm transactions and protect the network. Applications rely on software development tools, data services, security systems, node providers, and systems that connect blockchains to external information. Custodians protect private keys for institutions and individuals. Market makers provide liquidity. Analytics firms track transactions and risk. Payment companies connect digital assets with merchants and banking systems. Bridges and interoperability protocols attempt to move information or assets between different networks.
This infrastructure matters because blockchains do not operate in isolation. A lending protocol, for example, may depend on a blockchain for settlement, a stablecoin for its unit of account, an oracle service for market prices, a wallet for user access, and a bridge or exchange for moving assets into the system. A weakness in any one of these components can affect the entire application. The crypto market is therefore better understood as a collection of interconnected systems than as a simple list of coins competing for investor attention.
There is also an increasingly important institutional layer. Asset managers, banks, payment companies, trading firms, and technology providers have explored or adopted different forms of blockchain-based infrastructure. Their interest is not always based on the belief that cryptocurrency prices will rise. Institutions may be interested in faster settlement, round-the-clock markets, programmable transactions, new forms of collateral management, lower reconciliation costs, or easier distribution of financial products. Some experiments will fail to produce meaningful advantages, while others may gradually become part of mainstream financial operations. The relevant question is not only which token benefits, but whether the technology improves a specific economic process.
Market structure adds another dimension. Crypto trading takes place across centralized exchanges, decentralized exchanges, derivatives venues, over-the-counter markets, and peer-to-peer networks. Spot prices are influenced by leverage, liquidity, futures positioning, options markets, arbitrage, and the movement of stablecoins between platforms. A price visible on a mobile app is therefore the end result of a complex interaction among traders, automated systems, exchanges, collateral, and liquidity providers. During periods of stress, problems in one part of this structure can spread quickly through liquidations or sudden withdrawals of capital.
Regulation is equally important because crypto sits at the intersection of several established legal categories. Depending on the asset and activity, regulators may consider questions involving securities law, commodities, banking, payments, consumer protection, taxation, money laundering, and custody. Different jurisdictions often take different approaches, and legal treatment can shape which products are available, where companies operate, and how institutions participate. Regulatory developments can therefore influence the ecosystem even when cryptocurrency prices do not immediately react.
Looking beyond prices also helps distinguish speculation from adoption. A rapidly rising token can attract attention without creating lasting economic value. Conversely, a technology can become more useful while its associated asset remains stagnant or volatile. Adoption can appear in less dramatic forms: more stablecoin payments, greater liquidity in decentralized markets, stronger custody solutions, more efficient settlement, increasing developer activity, or the migration of traditional financial instruments onto blockchain-based systems. These developments may not produce exciting daily charts, but they provide a clearer view of whether the ecosystem is becoming more functional.
None of this means that prices are irrelevant. They influence investor behavior, access to capital, mining or validator economics, collateral values, and the willingness of developers and companies to enter the sector. Bull markets often accelerate investment and experimentation, while prolonged declines can expose weak business models and force projects to become more disciplined. Prices are therefore an important signal, but they are only one signal among many.
A fuller understanding of crypto comes from seeing it as a developing financial and technological ecosystem rather than a collection of speculative assets. Cryptocurrency quotations show what the market is willing to pay for certain tokens at a particular moment. They do not, by themselves, reveal how much value is being transferred through stablecoins, how much capital is being deployed in financial protocols, which assets are being tokenized, how infrastructure is evolving, or whether institutions are adopting blockchain-based systems. Those quieter layers may ultimately matter more than the daily movements that dominate headlines. The price chart is the part of the crypto market everyone can see; the networks, protocols, markets, and financial infrastructure underneath it are what make the ecosystem much larger than the chart itself.
