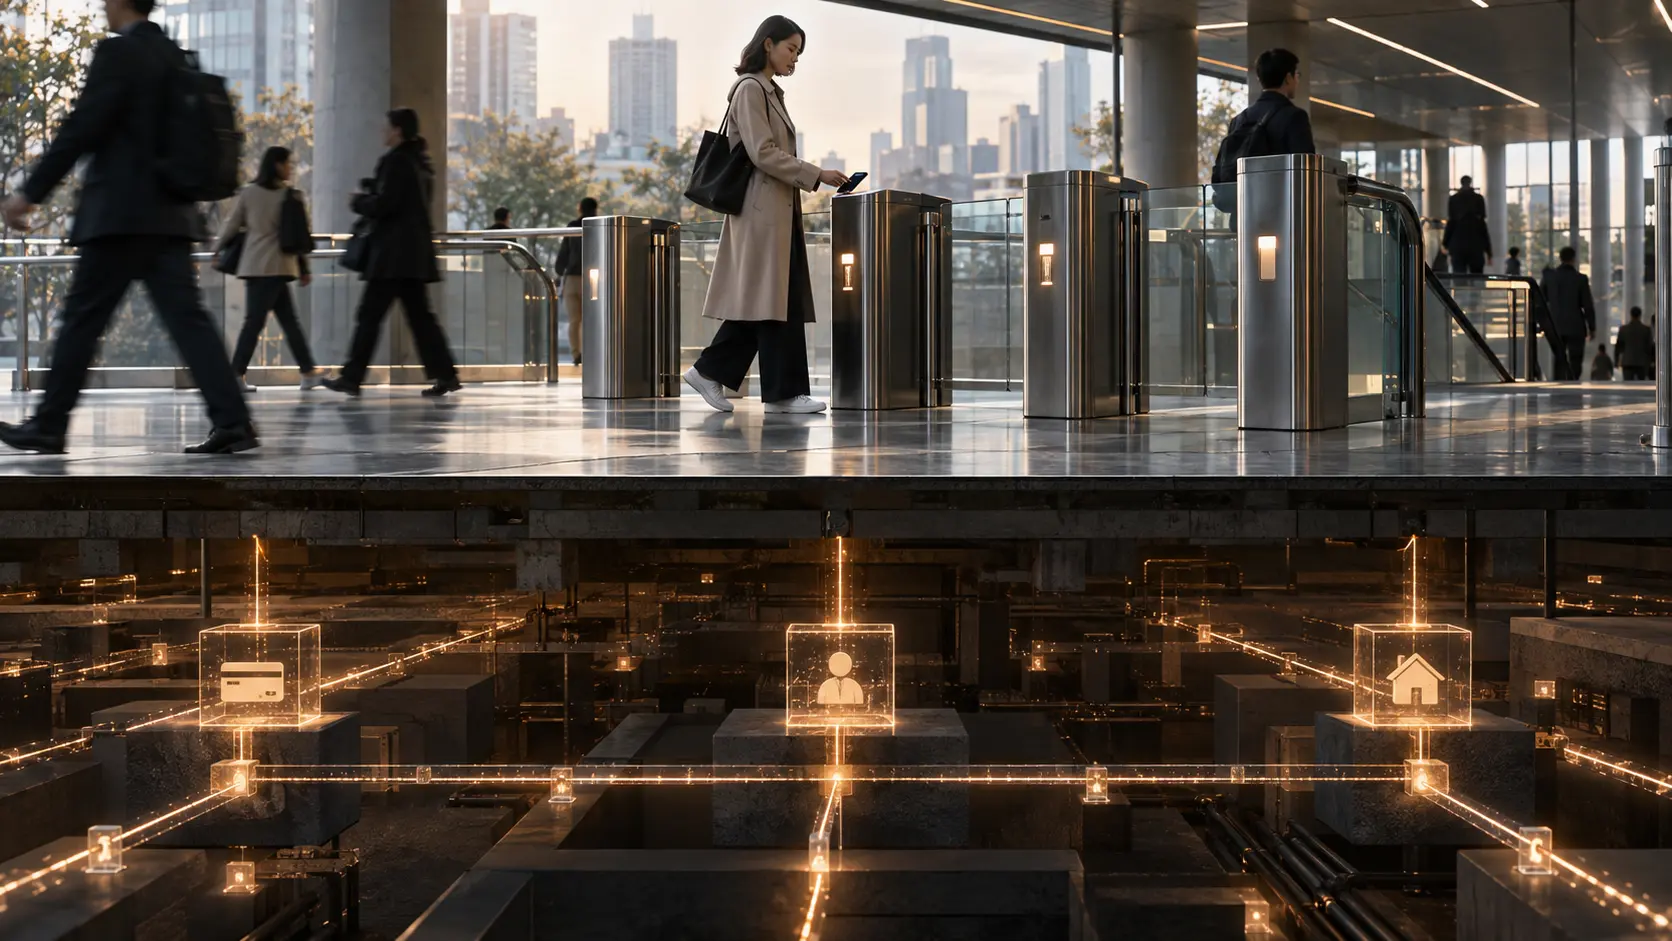
The future of crypto may look less like millions of people learning to manage wallets and more like blockchain technology disappearing from view. Mature technologies often become most successful when users no longer need to think about the infrastructure underneath them. People send messages without thinking about internet protocols, pay with cards without understanding settlement networks, and store files in the cloud without knowing which data center holds them. Blockchain could follow the same path: becoming less visible as a product and more important as infrastructure.
That possibility changes the way crypto adoption should be understood. Adoption does not necessarily mean that everyone will hold volatile cryptocurrencies, memorize recovery phrases, or interact directly with decentralized applications. It may instead mean that financial services, payment systems, digital assets, and autonomous software begin using blockchain-based settlement or ownership records while presenting users with familiar interfaces. The blockchain remains underneath, but the experience above it looks increasingly ordinary.
Stablecoins already point in this direction. A user may eventually send what appears to be a dollar payment through an application without needing to know whether the transaction was settled through a bank ledger, a card network, or a public blockchain. The application can display a balance in dollars, handle the wallet infrastructure, calculate fees, and abstract away technical details such as network selection or token standards. From the user's perspective, the important facts are that the payment arrived, the amount remained stable, and the service was easy to use.
Behind that simple experience, however, the infrastructure can be quite different from a conventional bank transfer. The payment may involve a stablecoin moving between blockchain addresses, with reserves held through banks or invested in short-term government securities. The user sees dollars; the system sees tokens, cryptographic signatures, blockchain finality, and redemption mechanisms. This is a good example of how crypto infrastructure can expand without requiring crypto terminology to remain visible.
Such abstraction would represent a major change from the early experience of blockchain applications. Historically, users often had to understand which network they were using, maintain their own keys, acquire a native token to pay transaction fees, copy long addresses, and recognize the difference between multiple versions of the same asset. These requirements exposed the machinery directly. They were comparable to asking internet users to understand routing protocols before visiting a website.
A more mature financial interface can hide much of that complexity. Applications can manage network fees behind the scenes, convert between assets automatically, present human-readable identities, and use account-recovery systems that do not require every user to protect one irreplaceable secret. The blockchain can continue providing settlement and programmability while the interface absorbs the operational burden.
This does not necessarily mean returning entirely to centralized custody. New wallet architectures can distribute recovery authority, impose spending rules, and allow users to retain meaningful control without forcing them to manage raw private keys. Some services may remain fully custodial, while others may use smart accounts or other systems in which control is shared or recoverable. The important point is that users do not need to experience every security mechanism directly for that mechanism to exist.
Tokenization could make blockchain infrastructure even less visible. A person buying a share in a bond fund may not care whether the ownership record is maintained entirely in conventional securities databases or partly through a blockchain. If tokenization improves settlement, reduces reconciliation, or makes the asset easier to integrate with other financial services, the benefit can occur behind the interface.
The underlying product can remain familiar. A government bond does not become economically different because a blockchain is involved in its ownership record. A fund does not stop being a fund because its shares are represented as tokens. If financial institutions eventually use blockchain systems as internal or shared infrastructure, most investors may continue seeing ordinary account balances, transaction histories, and investment products.
This is similar to what happened during earlier stages of financial digitization. Consumers did not need to understand the database architecture behind electronic securities trading for paper certificates to become largely irrelevant. Infrastructure changed while the economic products remained recognizable. Blockchain may ultimately matter in the same way: not because every asset becomes culturally associated with crypto, but because some of the records and settlement mechanisms underneath finance change.
Stablecoins and tokenized assets become particularly interesting when combined. If both money and securities can move on compatible digital infrastructure, financial transactions can potentially settle more directly. Software can coordinate the transfer of the asset and payment, manage collateral, distribute income, and enforce certain transaction rules. The investor may simply press “buy,” while several blockchain-based operations occur behind that one instruction.
This could produce systems that are neither fully traditional nor fully decentralized. A regulated financial institution might control the customer relationship and identity verification while public or permissioned blockchain infrastructure handles portions of settlement. A stablecoin issuer might depend on conventional banks and government securities while its tokens circulate through open networks. A tokenized asset might rely on a traditional custodian while smart contracts automate transfers among authorized participants.
These hybrids are important because the future of financial technology rarely involves one system replacing another in a single step. New infrastructure tends to coexist with older infrastructure, connecting to it where necessary and replacing only the parts where it offers a clear advantage. Blockchain does not have to eliminate banks, custodians, exchanges, or securities law in order to become significant. It can become one layer through which those institutions operate.
Artificial intelligence may accelerate this process because software agents care much less about financial branding than humans do. An autonomous agent does not need a familiar banking interface. It needs a reliable way to obtain resources, pay for services, receive funds, and operate within a defined budget. If blockchain-based assets provide useful programmable settlement, the agent can use them without experiencing the ideological distinction between “crypto” and “traditional finance.”
This creates an environment in which machines may become significant users of blockchain infrastructure before ordinary people consciously do. An AI agent could pay for computing resources with a stablecoin, acquire access to a dataset, settle a small obligation with another agent, or move funds between approved financial services. The human operator may see only a monthly expense report showing dollars spent on infrastructure.
The blockchain becomes analogous to an underlying communications protocol. Agents can use it because it is machine-readable, programmable, and available across organizational boundaries. Whether the user recognizes that a particular payment involved a token may be irrelevant. The economic function matters more than the label attached to the infrastructure.
This does not mean every AI agent will need blockchain. If all transactions take place inside one company's platform, an ordinary internal database may be simpler. Blockchain becomes more useful when independent systems need a shared settlement mechanism and do not want one participant to control the common ledger. The same criterion applies more broadly to hidden crypto infrastructure: it should remain because it solves a real problem, not because disguising it makes unnecessary blockchain use more acceptable.
The disappearance of visible crypto terminology could actually make this distinction clearer. During speculative cycles, products can attract attention merely by associating themselves with tokens, decentralization, or blockchain. If users stop caring which technology operates in the background, infrastructure will have to justify itself through cost, reliability, interoperability, programmability, or some other practical advantage. Blockchain would compete as infrastructure rather than as a narrative.
This could also change the role of native cryptocurrencies. Some blockchains require their own assets to compensate validators, pay transaction fees, or secure the network. Users of applications built on top of those networks may not need to hold those assets directly. A service could pay the required network fee behind the scenes and charge the user in dollars or incorporate the cost into its normal pricing. The native asset remains essential to the protocol while disappearing from the customer experience.
The distinction is similar to the relationship between consumers and cloud computing. A person using an online application does not purchase server time or manage data-center electricity directly, even though those resources are essential to the service. An application using blockchain infrastructure can likewise translate protocol-level costs into an ordinary service fee.
Cross-chain complexity may also become invisible. Today, users can face difficult decisions about which blockchain contains an asset, which bridge to use, and whether two versions of a token are actually equivalent. A mature application could route transactions across networks automatically according to cost, liquidity, security, and availability. Users would specify an economic intention—send $100, buy an asset, post collateral—while infrastructure determines how to execute it.
That abstraction could improve usability, but it does not make the underlying risks disappear. If an application uses a bridge behind the scenes, bridge security still matters. If it settles with a stablecoin, reserve and redemption risk still matter. If a token represents an external asset, legal enforceability still matters. Invisible infrastructure can make technology easier to use while making careful system design even more important.
This creates a paradox. As blockchain becomes less visible to users, users may become less capable of evaluating the technical dependencies themselves. They may no longer know which network processed a transaction or which smart contracts were involved. Responsibility therefore shifts toward the applications, institutions, and standards selecting that infrastructure. Abstraction improves usability by concentrating technical judgment elsewhere.
The same happened with other mature technologies. Ordinary internet users rely on browsers, operating systems, cloud providers, certificate authorities, and network operators without personally auditing them. Security comes partly from standards, professional management, regulation, competition, and institutional accountability. If blockchain becomes background financial infrastructure, a similar ecosystem may develop around it.
Regulation is likely to reinforce this shift. When blockchain services become integrated into regulated payment, investment, and custody systems, users may interact primarily with institutions that provide familiar protections and interfaces. Compliance, reporting, identity verification, and customer support can exist above blockchain settlement. The presence of decentralized infrastructure underneath does not require the entire service to be decentralized.
This makes the question “Is this crypto?” increasingly difficult to answer. A dollar token backed by conventional securities and transferred on a public blockchain belongs partly to both worlds. A traditional fund whose shares settle through distributed-ledger infrastructure does as well. An AI agent that pays a regulated service with stablecoins is using crypto technology without necessarily participating in what people traditionally think of as a crypto market.
The categories begin to matter less as the interfaces multiply. What was once called decentralized finance can borrow institutional custody and regulated assets. Banks can use tokenized deposits or blockchain settlement. Asset managers can offer traditional investments represented through tokens. Exchanges can connect blockchain-native assets to conventional investment products. The result is not a victory of one financial system over another but a growing stack of interconnected technologies.
There are still reasons blockchain may remain visible in some contexts. Self-custody users may value direct interaction precisely because they want to know which network they are using and retain control of their keys. Developers may need detailed access to protocol mechanics. Investors may deliberately hold native crypto assets because their monetary or governance properties matter. The disappearance of blockchain from ordinary interfaces does not imply the disappearance of direct use.
Instead, the ecosystem can split into layers. Specialists and users who value direct control can interact with protocols themselves, while most people access the same infrastructure through simplified applications. The internet works in a similar way: engineers can inspect packets and configure servers while ordinary users interact with websites and apps.
This is arguably a stronger vision of technological maturity than requiring everyone to become a blockchain expert. A technology that can provide useful infrastructure only when users understand its internal mechanics remains difficult to scale. A technology that becomes reliable enough to fade into the background can support far more activity.
The same principle applies to terminology. People may eventually talk about instant international payments rather than stablecoin transfers, digitally settled funds rather than tokenized securities, or autonomous purchasing agents rather than AI wallets. The blockchain component can remain economically significant while disappearing linguistically.
That would also make measuring adoption more complicated. The number of people who describe themselves as crypto users could become a poor indicator of how much economic activity relies on blockchain infrastructure. Someone might hold tokenized financial assets in a conventional investment account, receive an international payment settled through a stablecoin, and use a service whose AI agents pay one another on-chain without ever installing a crypto wallet.
The important measure would shift from visible participation to infrastructural dependence. How much settlement uses blockchain networks? How many financial claims are represented on programmable ledgers? How often do digital services use tokenized money behind the scenes? These questions describe a different kind of adoption from the speculative adoption associated with buying cryptocurrencies.
That future is not guaranteed. Traditional databases and payment systems are efficient for many purposes, and blockchain infrastructure must justify its additional complexity. Privacy, scalability, governance, interoperability, legal recognition, and security remain significant challenges. Some experiments will likely discover that blockchain adds little and return to simpler architectures.
But the technologies that persist may do so precisely because users stop noticing them. Stablecoins could become payment and settlement instruments without being presented primarily as crypto investments. Tokenization could alter securities infrastructure without changing the economic products investors buy. AI agents could transact through blockchain wallets without their human operators managing those wallets manually. Hybrid financial systems could combine banks, custodians, smart contracts, public networks, and traditional assets in ways that make the old boundary between crypto and conventional finance increasingly artificial.
The most consequential future for crypto may therefore be less visible than its past. Early adoption required users to confront the technology directly: wallets, tokens, network fees, seed phrases, exchanges, and unfamiliar financial concepts. Mature adoption could reverse that relationship. Users would interact with products and services, while blockchain becomes one of several invisible systems responsible for moving value and recording rights underneath them.
If that happens, crypto will not have succeeded because everyone started thinking in crypto terms. It will have succeeded in certain areas because people no longer needed to. The technology would remain present in settlement, ownership, programmable finance, and machine-to-machine transactions while disappearing from much of the visible experience. For infrastructure, becoming ordinary enough to be ignored can be a sign not of irrelevance, but of maturity.
