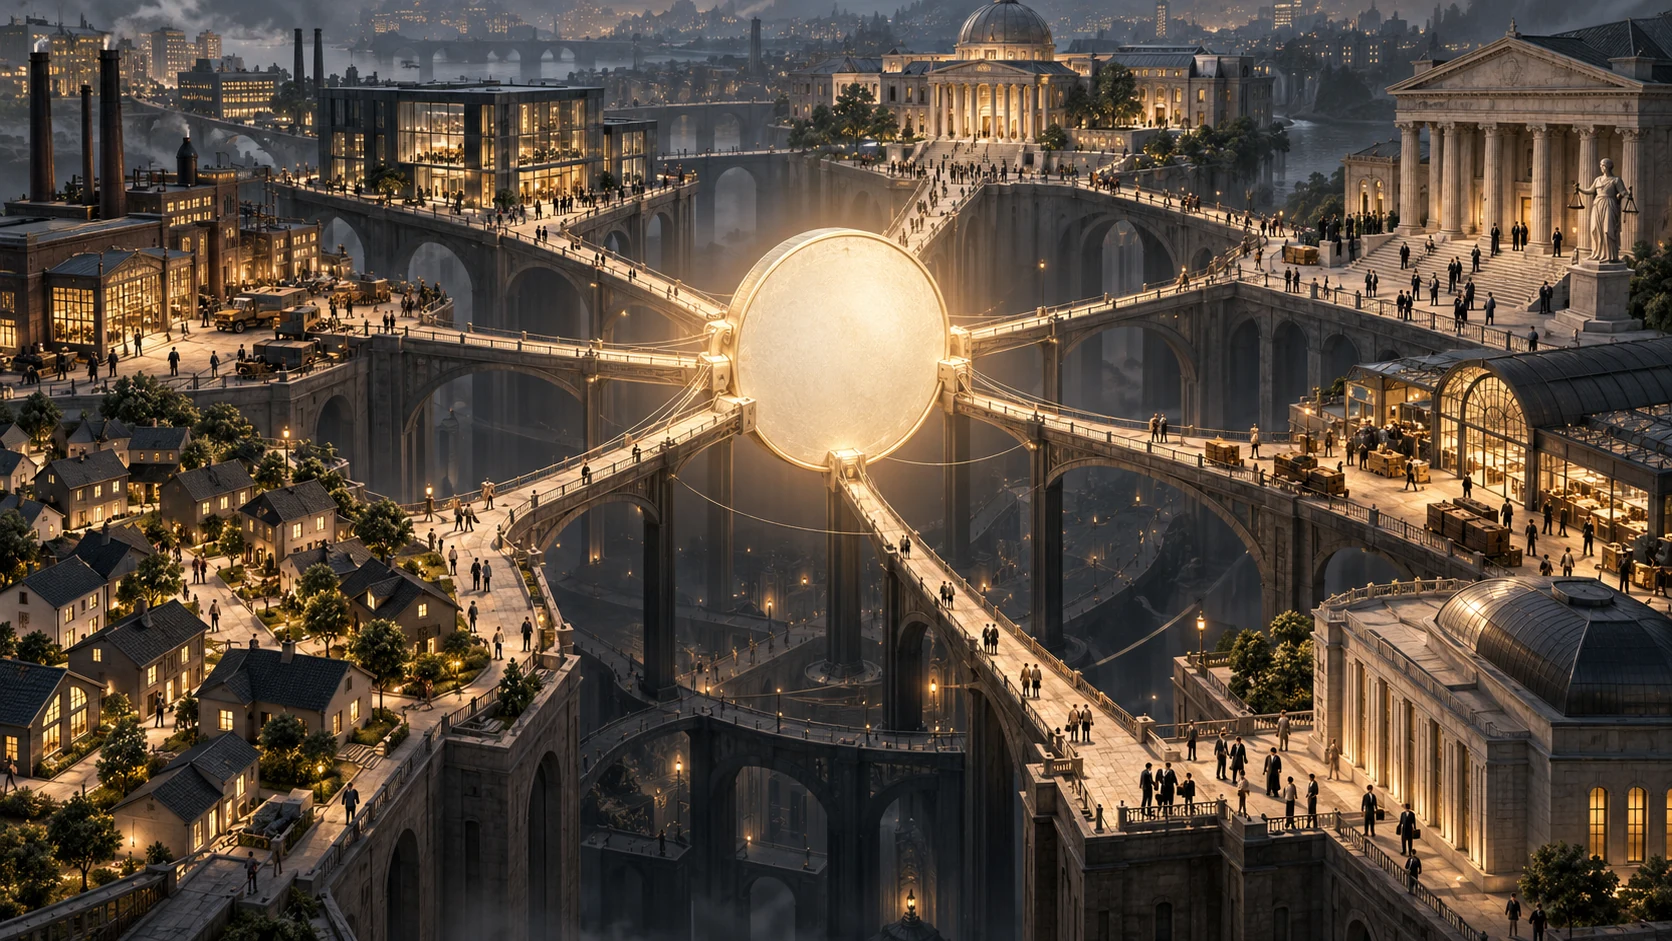
Money has value because people expect other people to accept it. A banknote is only a piece of printed material, a coin is only metal, and a bank balance is only a number recorded in a financial system. None of these things is especially useful on its own. Their monetary value comes from the fact that they can be exchanged for goods, services, assets, and the settlement of debts. Money works because there is a shared expectation that it will continue to be accepted.
This shared acceptance is not merely a matter of habit. It is supported by institutions, laws, contracts, payment systems, banks, and the state. Governments usually designate an official currency for public payments, collect taxes in it, pay employees and suppliers with it, and write many legal obligations in terms of it. Courts enforce contracts denominated in that currency, while banks and payment networks make it possible to transfer claims from one person to another. Together, these arrangements make the currency deeply embedded in economic life.
Taxes are particularly important because they create a recurring demand for the official currency. If households and businesses owe taxes in dollars, pounds, euros, or another national currency, they have a practical reason to obtain that currency. This does not mean taxation alone explains the entire value of money, but it strengthens the monetary system by tying the currency to obligations that people cannot simply ignore. The state also reinforces its currency by using it as the unit in which public budgets, fines, salaries, and many other payments are expressed.
Private contracts add another layer. Wages, rents, mortgages, business invoices, insurance policies, and loans are commonly written in the same unit of account. Once large parts of economic life are organized around a particular currency, switching to something else becomes costly and inconvenient. The more people use a currency, the more useful it becomes, because every participant knows that others are already prepared to accept it. Economists often describe this as a network effect: the usefulness of the system grows with the number of people participating in it.
Trust is therefore central, but it is not the same as blind faith. People accept money because they have reasonable grounds to expect that the system around it will continue functioning. They trust that banks will process payments, that merchants will accept deposits and banknotes, that contracts will be enforced, and that the currency will not suddenly lose most of its purchasing power. Confidence is supported by institutions, but it can also be weakened when those institutions fail.
Inflation shows why confidence alone is not enough. A currency may continue to be widely accepted even while its purchasing power declines. If prices rise, each unit of money buys fewer goods and services than before. People may still use the currency because they need it for everyday transactions and legal obligations, but their willingness to hold large amounts of it can weaken. In extreme cases, when inflation becomes very high and persistent, people may try to spend money quickly, save in foreign currencies, or move into assets they believe will preserve value better.
The value of money therefore depends partly on expectations about the future. When someone accepts payment today, that person is usually doing so because the money is expected to remain useful tomorrow. A shopkeeper who takes a bank deposit in exchange for food does not want the deposit for its own sake. The shopkeeper expects to use it later to pay suppliers, workers, taxes, rent, or personal expenses. Every monetary transaction contains this forward-looking element.
Modern money also depends heavily on confidence in financial institutions. Most money used in everyday life does not exist as physical cash but as bank deposits. A bank deposit is a claim on a bank, which means its usefulness depends on confidence that the bank can honor payments and withdrawals. Regulation, deposit insurance, central banks, and payment infrastructure help make deposits reliable enough to function as money. People rarely think about these institutional foundations when using a debit card, but they are part of what makes the transaction possible.
It is also important to distinguish the value of money from the material from which it is made. Some historical currencies were made from precious metals, and the metal itself had market value. Modern fiat currencies work differently. Their face value is generally much greater than the value of the paper, polymer, or metal used to produce them. A hundred-dollar note is not valuable because its physical material is worth one hundred dollars. It is valuable because the monetary system recognizes it as a claim with a certain purchasing power.
This helps explain why attempts to say that modern money is backed by a single physical object can be misleading. In most contemporary systems, currency is not redeemable for a fixed amount of gold or silver. Its value instead depends on the economic and institutional framework in which it operates. That includes the productive capacity of the economy, the credibility of public institutions, monetary and fiscal policy, the stability of the banking system, and the willingness of people to continue using the currency.
The productive capacity of an economy matters because money ultimately buys real things. A society may create more units of currency, but it cannot create food, housing, energy, machinery, medical care, or skilled labor merely by increasing the number of monetary claims. If the amount of spending rises much faster than the economy's ability to produce goods and services, prices can increase. Money is therefore useful because it gives people claims on real resources, but the existence of more money does not automatically mean the existence of more real wealth.
This is where the distinction between money, wealth, and value becomes important. Money is a medium used to make payments, measure prices, and store purchasing power. Wealth is broader. It can include homes, land, businesses, machinery, intellectual property, financial assets, and other resources that provide economic benefits. Someone can hold little cash but own substantial wealth, while another person can temporarily hold a large amount of money without being especially wealthy once debts and obligations are considered.
Value is broader still. In economics, value often refers to what people are willing to give up to obtain something, but not everything people value is measured well by money. Clean air, personal relationships, security, free time, knowledge, and cultural heritage can all matter greatly even when they do not have simple market prices. Money provides a common way to compare many economic exchanges, but it is not a complete measure of everything that matters.
Because money is a social institution, its stability depends on a balance between confidence and economic reality. A currency cannot retain purchasing power merely because a government declares that it should, but neither is it valuable only because individuals spontaneously agree to use it. Its strength comes from a combination of collective acceptance, enforceable obligations, functioning institutions, productive capacity, and expectations about the future. When these elements reinforce one another, money can remain stable and widely trusted for long periods.
What gives money its value, then, is not the paper, metal, or electronic record itself. It is the network of relationships and expectations surrounding it. People accept money because others accept it, because debts and taxes are settled with it, because institutions support its use, and because they expect it to retain enough purchasing power to be useful later. Money is valuable because it functions as a dependable claim within an organized economy, but the real wealth behind that economy lies in the goods, services, skills, resources, and productive capacities that money allows people to exchange.
