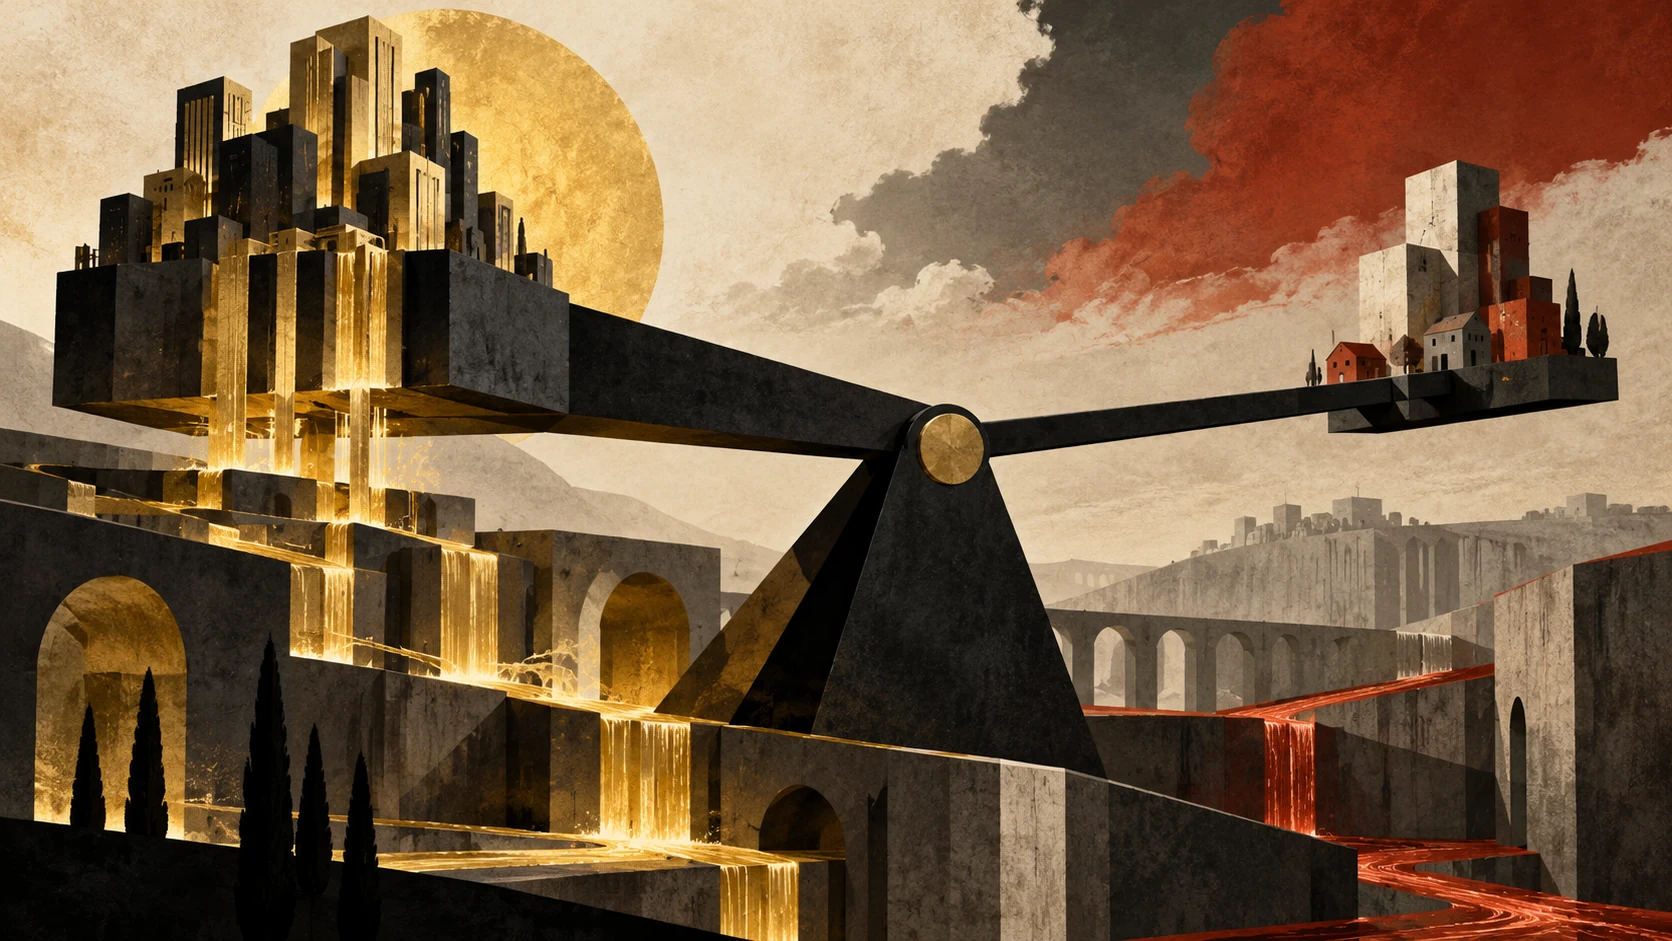
Economic power is the ability to influence economic decisions, shape the conditions under which exchanges take place, and affect what other people, businesses, or institutions are able to do. Wealth can be an important source of this power, but the two are not the same. A person may possess a large amount of wealth without having much influence over production, employment, credit, or essential resources. Conversely, an institution may exercise considerable economic power because it controls something others depend on, even if its wealth is not especially large compared with the wealthiest actors in the economy.
This distinction matters because economies are not made up only of voluntary exchanges between individuals who enter markets on equal terms. People and organizations come to those exchanges with different resources, different obligations, different alternatives, and different capacities to withstand delay or failure. A worker who urgently needs income, a business that must refinance debt within days, a landlord who can leave a property vacant for months, and a bank deciding whether to renew a credit line do not occupy equivalent positions. Their choices are shaped not only by prices but also by the power each side possesses.
At its most basic level, economic power comes from control over things that others need or value. These may include land, factories, housing, technology, transportation networks, energy systems, financial capital, patents, data, specialized knowledge, or access to markets. Control matters because resources become economically significant not simply when someone possesses them, but when that possession affects the options available to others. Ownership of an isolated asset that nobody needs creates little influence. Control of a scarce resource that many people depend on can create substantial power.
Property rights are therefore one of the foundations of economic power. Property does more than identify who legally owns an object. It establishes who can use an asset, exclude others from it, transfer it, rent it, pledge it as collateral, or receive income from it. Someone who owns productive assets can often decide whether those assets will be used, under what conditions, and by whom. An owner of land may determine whether it is developed or left unused. A company controlling a factory may decide what is produced, how investment is allocated, and which workers are employed. A firm that owns a critical patent may restrict access to a technology unless others accept its terms.
Yet ownership alone does not explain the distribution of economic power. Control can be separated from formal ownership. Shareholders may legally own a corporation while executives exercise much of the practical authority over its daily operations. Governments may own infrastructure while private contractors manage important parts of it. Financial institutions may not own the companies to which they lend, but loan conditions can strongly influence those companies' behavior. Large customers may exert pressure over suppliers without owning them at all. Economic power therefore concerns effective control and dependence as much as legal title.
The control of resources becomes especially powerful when alternatives are limited. If many competing suppliers can provide the same product, any one supplier usually has less leverage. If only one or two firms control access to an essential input, customers may have little choice but to accept their conditions. This is one reason market concentration matters. A company with a dominant position may be able to influence prices, wages, contract terms, technological standards, or the survival of smaller firms. Its power does not arise merely from being large. It arises from the dependence of others on resources, services, or market access that the company can grant or withhold.
Credit is another major source of economic power because modern economies depend heavily on promises about future payment. Households borrow to purchase homes, businesses borrow to invest or survive temporary losses, and governments borrow to finance expenditures. Those who control access to credit can therefore influence activities far beyond their own immediate spending. A bank that refuses a loan may prevent an investment from occurring. An investor who withdraws financing may force a company to change strategy. A creditor facing a heavily indebted borrower can sometimes demand conditions that would be impossible to impose on someone who could easily obtain financing elsewhere.
This is why financial wealth can generate more power than its face value might suggest. Money is unusually flexible. A factory is useful for particular kinds of production, while financial assets can often be redirected across industries, regions, and investment opportunities. Liquid wealth can purchase property, finance businesses, acquire competitors, survive losses, or wait for more favorable conditions. It therefore provides not only purchasing power but also strategic flexibility.
The ability to wait is one of the most overlooked forms of economic power. Economic decisions often occur under pressure, and the side that can tolerate delay usually has an advantage. Consider a worker negotiating wages while facing rent, food, and debt payments. If the worker cannot remain unemployed for long, the need for immediate income weakens the ability to reject an unfavorable offer. An employer with sufficient reserves may be able to leave a position unfilled for longer. The formal negotiation may be voluntary for both sides, but their ability to walk away is different.
The same principle appears throughout the economy. A homeowner forced to sell quickly may accept a lower price than someone who can wait for a better buyer. A small supplier dependent on a single large customer may accept delayed payments because losing the contract would threaten its survival. An investor holding cash during a crisis may purchase assets cheaply from owners who urgently need liquidity. Economic power therefore depends partly on what economists sometimes describe as the quality of one's outside options: what happens if an agreement is rejected.
This leads directly to bargaining power. Every economic agreement distributes benefits and costs between parties. Wages divide the income generated by production between workers and employers. Rent determines how much of a tenant's income goes to a property owner. Interest rates and loan conditions allocate risks and returns between borrowers and lenders. Supplier contracts determine prices, payment schedules, quality requirements, and liability. In all these cases, outcomes depend partly on bargaining power.
Bargaining power is stronger when a person or organization has good alternatives and weaker when alternatives are scarce. A highly specialized employee with several competing job offers can usually negotiate differently from a worker facing high unemployment. A retailer that can choose among hundreds of suppliers has more leverage than a supplier whose sales depend overwhelmingly on that retailer. A country able to obtain financing from many sources is less vulnerable to the demands of a single creditor than one facing a severe shortage of foreign currency.
Economic power can therefore exist even when nobody explicitly gives an order. A dominant customer may never command a supplier to lower wages, yet its insistence on lower prices can create pressure that travels down the supply chain. A lender may not directly manage a company, but the possibility of withdrawing credit can influence corporate decisions. Owners of scarce housing do not need to instruct tenants about their broader financial choices; high rents themselves may reduce what tenants can spend elsewhere. Power often operates through the structure of available choices rather than through direct commands.
Infrastructure makes this especially clear. Roads, ports, railways, electricity grids, telecommunications systems, payment networks, digital platforms, and logistical hubs enable other economic activities to occur. Control over such systems can create influence because many participants depend on them simultaneously. The owner or operator of a critical network may affect which businesses can reach customers, how much access costs, what technical standards must be followed, and which activities are economically viable.
Network effects can strengthen this kind of power. A service may become more valuable as more people use it, making it increasingly difficult for competitors to attract users. Digital platforms provide familiar examples, but the principle is older than the internet. Transportation networks, marketplaces, exchanges, and communication systems can all become more useful when many participants converge on the same system. Once that happens, controlling access to the network may be more economically important than simply owning a large quantity of conventional assets.
Scarcity also plays a central role. Economic power tends to increase when a controlled resource is difficult to replace. A common resource available from many sources usually gives its owner little bargaining leverage. A rare mineral essential to a particular technology, a uniquely located piece of land, a specialized production process, or a crucial distribution channel may provide much greater influence. The relevant question is not only how valuable the resource is, but how easily others can substitute something else for it.
This helps explain why wealth should not be treated as a complete measure of power. Imagine two wealthy individuals. One holds a diversified portfolio of passive investments and has little involvement in the decisions of the firms represented in that portfolio. The other controls a much smaller company that happens to operate the only major transport link serving an isolated region. The first person may be richer, while the second may exercise more direct influence over the economic choices of people and businesses that depend on the transport system.
The reverse can also occur. An individual may hold an important managerial position and make decisions affecting thousands of employees without personally owning much capital. Senior executives, public officials, fund managers, regulators, and administrators can all exercise forms of economic power through authority over resources they do not personally own. Their power comes from institutional position rather than private wealth.
Organizations are therefore crucial to understanding economic power. Individuals rarely exercise large-scale influence alone. Corporations combine capital, legal rights, specialized knowledge, management structures, and large workforces. Banks pool savings and direct credit. Labor unions organize workers who would otherwise negotiate individually. Governments tax, spend, regulate, issue currency, enforce contracts, and provide public infrastructure. Pension funds and investment funds aggregate the wealth of millions of people and can become major shareholders. Economic power is often created by coordination.
Collective organization can change bargaining relationships dramatically. A single worker may be easily replaceable, while thousands of organized workers acting together can disrupt production and negotiate as a group. A small business may have little influence over a large platform, but an industry association can sometimes coordinate common demands. Consumers individually may have little leverage over a major supplier, while organized boycotts, cooperatives, or regulatory institutions can alter the balance. Power depends not only on what resources exist, but also on whether those who possess them can act together.
Information can also produce economic power. Markets function through decisions made under uncertainty, and parties rarely possess identical knowledge. A lender may know more about financial conditions than a borrower. A company may know more about its product than its customers. A digital platform may observe patterns of consumer behavior that individual merchants cannot see. Information can improve forecasting, pricing, negotiation, investment, and risk management. When information is difficult to obtain or concentrated in a few hands, it can become a strategic resource.
Knowledge and technical expertise work in a similar way. Complex economies depend on specialized skills that cannot always be replaced quickly. Engineers who understand a critical system, professionals with rare qualifications, or firms possessing difficult-to-copy technological knowledge may gain bargaining power because others rely on capabilities that take time to reproduce. Intellectual property law can reinforce this position by granting temporary exclusive rights over inventions, creative works, or brands.
Political and economic power also interact, although they should not be treated as identical. Governments create and enforce many of the rules within which economic activity occurs, including property rights, corporate law, labor standards, competition policy, financial regulation, taxation, and bankruptcy procedures. Economic actors therefore have incentives to influence public decisions. Wealth can help finance lobbying, political campaigns, legal challenges, research organizations, media activity, or other forms of participation in public debate.
At the same time, political institutions can limit economic power. Competition law may restrict monopolistic practices. Labor law may strengthen workers' negotiating position. Financial regulation can constrain lenders and investors. Public utilities may provide alternatives to private infrastructure. Bankruptcy law determines how losses are divided when debts cannot be repaid. Taxation can affect the accumulation and transfer of wealth. Economic power is therefore not a force that exists outside legal institutions; it is partly shaped by them.
This does not mean every economic inequality represents an abuse of power. Differences in wealth, ownership, expertise, size, or bargaining strength can arise for many reasons, including innovation, saving, risk-taking, inheritance, legal privilege, market success, historical circumstances, or simple scarcity. Nor does possessing economic power imply that it will always be used harmfully. A large organization may use its resources to invest in productive capacity, develop technology, stabilize supply, or reduce costs. The important analytical point is that unequal control over resources creates unequal capacities to influence outcomes.
Power also varies by situation. A company may be extremely powerful in one relationship and relatively weak in another. A manufacturer may dominate its small suppliers while depending heavily on a few major retailers. A wealthy borrower may negotiate favorable terms with one bank but remain vulnerable to a sudden change in government regulation. A country may control an important natural resource yet depend on foreign technology, shipping, or finance. Economic relationships often involve overlapping forms of dependence rather than a simple division between powerful and powerless actors.
For this reason, economic power is best understood relationally. Saying that someone possesses power is incomplete unless we ask: power over what, in relation to whom, and under what conditions? An employer's power matters in relation to workers seeking jobs. A creditor's power matters in relation to borrowers needing finance. A platform's power matters in relation to businesses requiring access to its users. A property owner's power matters in relation to people seeking scarce housing or land. The same asset can provide little leverage in one environment and substantial leverage in another.
Time can transform these relationships. Economic power may accumulate because resources generate additional resources. Property can produce rent, financial assets can produce returns, profitable businesses can reinvest earnings, and access to credit can make further acquisitions possible. Wealth can therefore become a mechanism for expanding control. At the same time, power can erode. New technologies can make old assets obsolete, competitors can enter a market, workers can organize, debts can overwhelm an investor, regulation can change, and consumers can shift toward substitutes.
Crises often reveal economic power that remains less visible during stable periods. When credit suddenly becomes scarce, institutions controlling liquidity become more influential. When supply chains break down, control over transportation, energy, food, or critical components becomes strategically important. When unemployment rises sharply, workers may lose bargaining power because employers have more applicants to choose from. When labor becomes scarce, the balance can move in the opposite direction. Economic power changes with the surrounding conditions because dependence itself changes.
The concept also helps explain why identical market prices can have different meanings for different participants. A higher interest rate may be inconvenient for a financially secure company but devastating for a heavily indebted one. A rise in rent may reduce discretionary spending for a wealthy household while threatening displacement for a poorer tenant. A temporary loss of income may be easily absorbed by someone with substantial savings but force another person to accept the first available job. Money prices are visible, but the capacity to respond to those prices is distributed unevenly.
Understanding economic power therefore requires looking beyond the amount of money someone possesses at a particular moment. Wealth matters because it expands choices, provides security, enables investment, and often increases bargaining strength. But economic power also comes from property, control over scarce resources, access to credit, ownership of infrastructure, organizational capacity, information, institutional authority, and the ability to endure delay. Above all, it comes from having alternatives when others do not.
Seen in this way, the economy is not merely a system for exchanging goods and services. It is also a network of relationships in which people and institutions depend on one another under unequal conditions. Prices, wages, contracts, investment, production, and access to resources emerge from those relationships. To understand who can shape economic outcomes, it is therefore necessary to ask not only who is wealthy, but who controls what others need, who can refuse an agreement, who can wait, who has alternatives, and who must act immediately. Those questions reveal economic power more clearly than wealth alone ever could.
