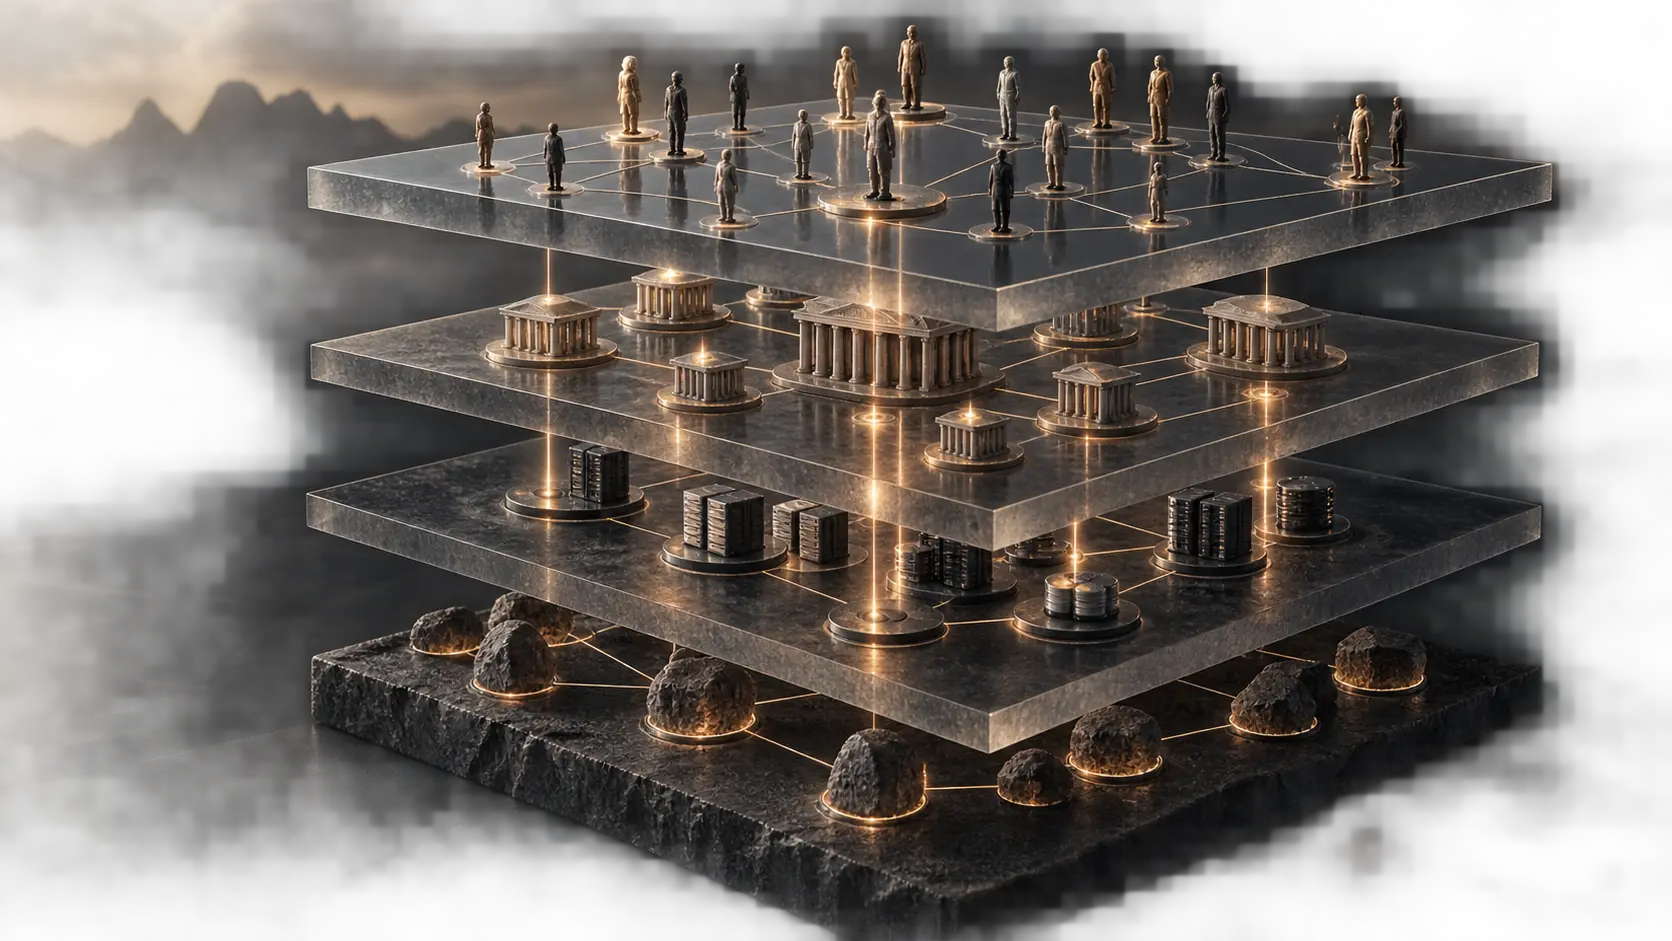
Decentralization is often discussed as if a blockchain were either decentralized or centralized. In practice, the distinction is rarely that simple. A crypto network can distribute power effectively in one area while concentrating it heavily in another. Consensus may involve many independent validators, for example, while development depends on a small core team, token ownership is concentrated among a few investors, and most users access the network through centralized exchanges. Understanding decentralization therefore requires looking at several layers separately rather than assigning a single label to an entire project.
The first layer is consensus, the mechanism through which a blockchain determines which transactions are valid and which version of the ledger participants accept. In proof-of-work networks, this involves mining power; in proof-of-stake networks, it generally involves validators and staked assets. The important question is how widely this power is distributed. A network can have many validators while a small number of large operators control most effective participation. Mining pools can produce a similar concentration even when individual miners are geographically dispersed. What matters is not only the number of participants but also how difficult it would be for a small group to coordinate, censor transactions, disrupt finality, or otherwise exercise disproportionate influence.
Consensus decentralization is important because it concerns the integrity of the ledger, but it says little about who develops the software itself. Development is a separate layer. Most major blockchain protocols depend on a relatively small number of people with the technical expertise, reputation, and access necessary to maintain core software. Source code may be publicly available, and anyone may theoretically propose changes, yet practical influence is rarely distributed equally. Experienced maintainers decide which proposals receive attention, write important implementations, review code, coordinate upgrades, and often shape the technical direction of the network.
This does not mean that core developers necessarily control a blockchain. In many systems, they cannot force users, validators, or node operators to adopt new software. Their influence depends partly on whether the wider ecosystem accepts their work. Still, development concentration matters because the ability to define technical options is itself a form of power. A network can therefore have highly distributed consensus while remaining dependent on a small development community.
Infrastructure forms another layer. Blockchains may allow anyone to run a node, yet nodes and applications still require servers, internet connections, data storage, development tools, application programming interfaces, and other services. Much of this infrastructure can be provided by a limited number of cloud companies or specialized blockchain firms. If a large share of validators, nodes, or applications relies on the same providers, the network may have dependencies that are not visible simply by counting participants.
Geographic concentration can create a similar issue. Thousands of nodes spread across different owners may still depend on a limited number of jurisdictions, data centers, or internet providers. Software concentration matters as well. If nearly everyone runs the same implementation of a blockchain client, a serious bug in that implementation could affect much of the network simultaneously. Infrastructure decentralization therefore involves diversity of providers, locations, software, and operational control, not merely the existence of many machines.
Token ownership adds another dimension. Crypto assets are often distributed unevenly. Founders, early investors, foundations, exchanges, venture funds, large holders, or other entities may control substantial portions of supply. Concentrated ownership can influence markets, staking, governance, and access to economic rewards. A network may be permissionless in principle while much of its economic power remains concentrated among a relatively small group.
The consequences depend on how the token functions. If ownership provides little direct control over the protocol, concentration may mainly affect markets and wealth distribution. If the token determines validator power or governance votes, ownership concentration can translate much more directly into control. It is therefore not enough to ask how many token holders exist. The distribution of voting rights, staking power, liquid supply, locked tokens, and delegated assets can all matter.
Interfaces create another layer that is frequently overlooked. Most people do not interact directly with blockchain protocols. They use websites, mobile applications, wallets, exchange platforms, dashboards, and other interfaces. The underlying smart contracts may be decentralized and accessible to anyone, but ordinary users may depend overwhelmingly on one or two popular front ends.
This distinction becomes important when an interface can restrict access, remove features, block jurisdictions, or stop operating. The underlying protocol may continue functioning, yet many users may find it difficult to reach it. A technically decentralized application can therefore have a centralized distribution layer. The ability to interact directly with smart contracts or switch easily to alternative interfaces makes this dependency less severe, but that ability varies considerably between projects and users.
Custody is another independent question. A user can own an asset issued on a decentralized blockchain while leaving control of that asset with a centralized exchange, custodian, or financial institution. In that situation, the blockchain may allow direct ownership, but the individual user is still dependent on an intermediary to access or transfer the asset. If the custodian freezes withdrawals, fails financially, or restricts an account, the theoretical decentralization of the underlying network offers limited protection to that particular user.
Self-custody changes this relationship because users control the cryptographic credentials necessary to move their assets. Yet self-custody introduces its own risks, including lost keys, compromised devices, malicious software, and operational mistakes. Decentralization therefore shifts responsibility rather than eliminating risk. The relevant analytical question is whether users have the option to hold and transact without a central custodian, not whether every participant actually chooses to do so.
Governance adds another complicated layer. Some networks have explicit voting systems in which token holders decide on funding, protocol parameters, upgrades, or treasury spending. Others rely more heavily on informal coordination among developers, validators, businesses, users, and community groups. Neither approach automatically produces broad decentralization.
Formal voting can be dominated by large holders or delegates. Low participation can allow a small group of active voters to determine outcomes for the entire network. Delegation can improve efficiency while also creating influential political blocs within the protocol. Informal governance avoids some of these mechanisms but can concentrate influence among prominent developers, foundations, companies, or community figures. Power exists even when it is not expressed through a formal vote.
These layers can produce combinations that make simple labels misleading. A blockchain might have resilient consensus and diverse infrastructure but concentrated token ownership. Another might distribute tokens widely while relying on a small set of validators. A decentralized finance protocol could have immutable smart contracts but depend heavily on a centralized website, a small governance committee, and a single external data provider. A network may therefore be difficult to control at the ledger level while remaining centralized in the ways most users actually experience it.
External dependencies complicate the picture further. Crypto applications often rely on stablecoins, bridges, oracles, custodians, and other systems that have their own governance and security structures. A lending protocol, for instance, can be decentralized at the smart-contract level but depend on a centralized stablecoin as collateral and a limited number of oracle providers for price information. If either dependency fails or changes its rules, the protocol can be affected even though its own contracts continue operating exactly as designed.
Decentralization should therefore be evaluated as a map of dependencies. For each important function, it is useful to ask who controls it, how many independent alternatives exist, what would happen if the dominant provider disappeared, and whether participants can replace that provider without asking permission. A system is more robust when power is distributed not only numerically but also functionally, so that the failure or capture of one actor does not determine the outcome for everyone else.
The ability to exit is particularly revealing. If users can switch validators, change wallets, run their own nodes, use alternative interfaces, replace service providers, reject unwanted upgrades, or fork software, concentrated influence becomes easier to resist. A powerful participant may still exist, but its authority is constrained if others can credibly leave or organize around alternatives. Decentralization is therefore partly about how costly it is to escape dependence.
This also explains why decentralization can change over time. A network may begin with a small development team and concentrated token ownership because early-stage projects naturally have few participants. If the ecosystem grows, ownership can spread, independent implementations can appear, infrastructure providers can diversify, and governance can become more distributed. The reverse can also happen. Economies of scale may push validators toward large operators, infrastructure may consolidate around a few providers, and passive token holders may delegate power to increasingly dominant entities.
None of these dimensions needs to be maximally decentralized for a system to be useful. Greater distribution can improve resistance to censorship, capture, and single points of failure, but it can also make coordination slower, technical decisions harder, and infrastructure more expensive. Different projects make different trade-offs. The important analytical task is to identify those trade-offs clearly rather than using decentralization as a vague claim of superiority.
Treating decentralization as layered produces a more realistic picture of crypto systems. Consensus determines who helps establish the ledger, development shapes the software, infrastructure determines how the network operates in practice, token ownership distributes economic influence, interfaces mediate access, custody determines who controls assets, and governance shapes collective decisions. Each layer can have its own centers of power and its own mechanisms for resisting them.
For that reason, asking whether a blockchain is decentralized is usually less useful than asking where it is decentralized, where it is concentrated, and what consequences follow from each arrangement. Decentralization is not a switch that turns on when a project adopts blockchain technology. It is a changing distribution of authority and dependency across multiple layers of a system, and understanding those layers reveals far more than a simple yes-or-no label ever could.
