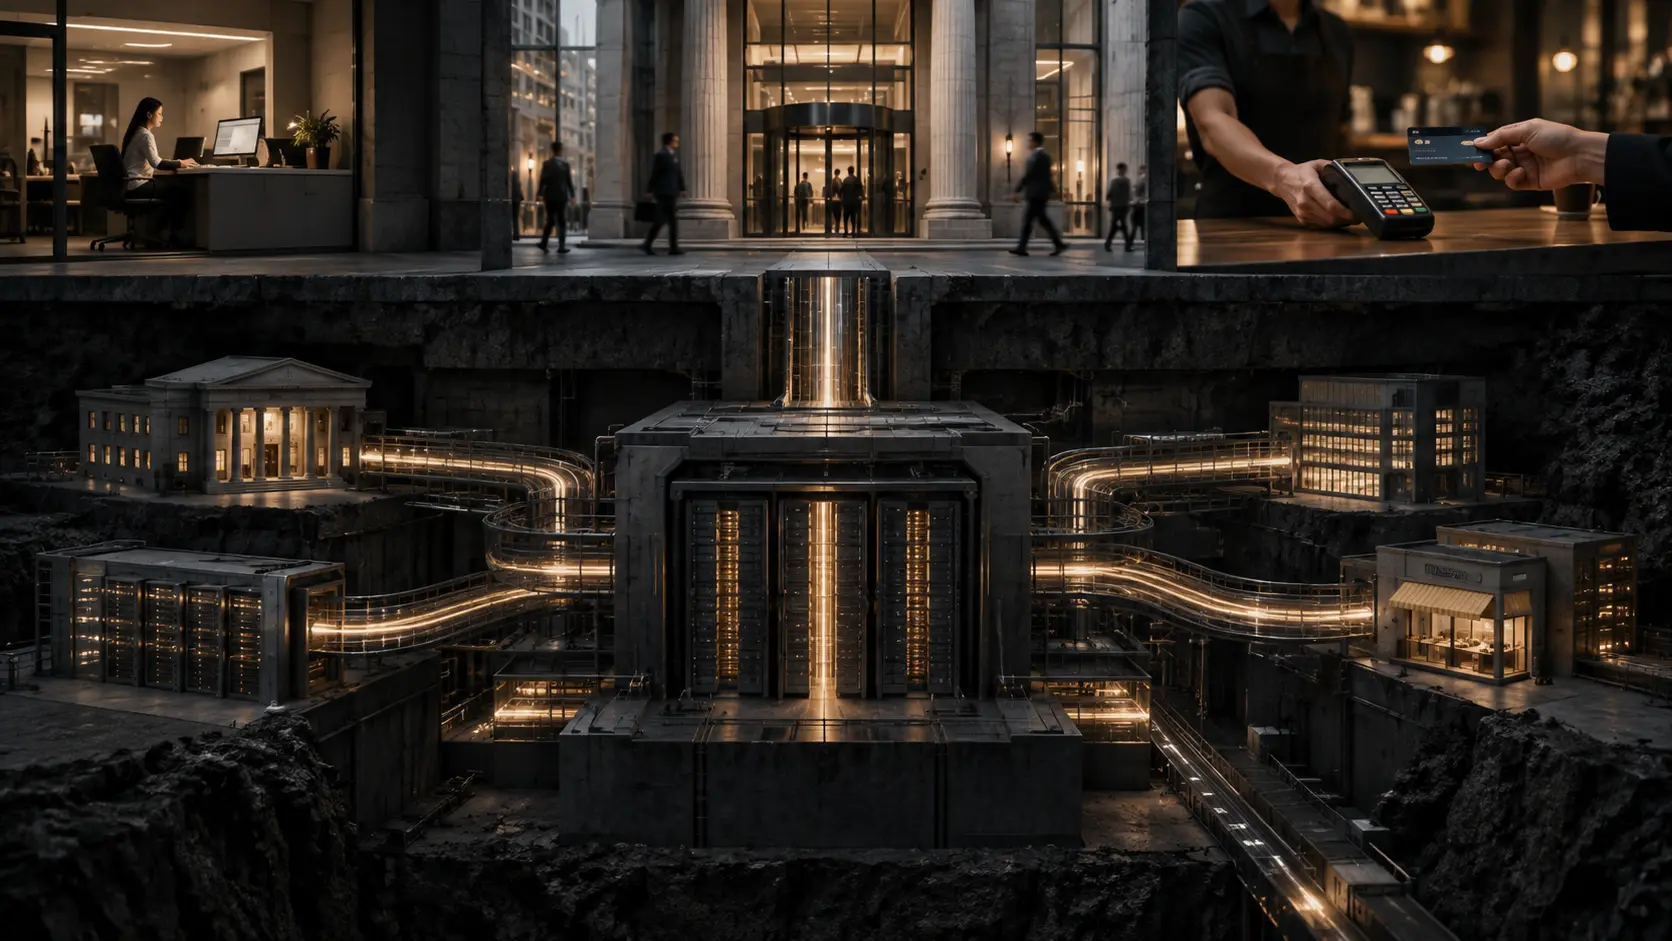
Long before Bitcoin appeared, most money in modern economies already existed in digital form. Salaries were deposited into bank accounts, card payments moved balances between institutions, businesses paid suppliers through electronic transfers, and banks settled enormous volumes of transactions without moving physical cash. For most people, money had already become something they encountered mainly as numbers on screens. Bitcoin did not invent digital money in that basic sense. Its innovation was more fundamental: it introduced a new way to maintain, verify, and transfer digital records without giving a central institution exclusive control over the ledger.
A bank account is essentially an entry in a financial institution's records. If someone has $1,000 in an account, there is not necessarily a box containing exactly $1,000 in cash with that person's name on it. The balance exists as part of the bank's accounting system, supported by the bank's assets, liabilities, legal obligations, and access to the broader financial system. When money is transferred from one bank customer to another, the important event is usually not the physical movement of notes. It is the updating of records: one balance decreases, another increases, and the institutions involved agree on the result.
Credit and debit cards work in a similar way. Tapping a card at a store does not cause money to travel instantly from a plastic card into a cash register. The payment generates messages between merchants, payment processors, card networks, banks, and other intermediaries. These systems determine whether the transaction is authorized, record what each party owes, and eventually settle the payment. Online banking, electronic payroll, wire transfers, and other forms of digital finance all depend on coordinated databases and trusted institutions that maintain authoritative records of ownership and obligations.
This makes the phrase "digital money" potentially misleading. Money can be digital while remaining highly centralized. The key question is not whether balances are represented electronically, but who has the authority to create, modify, confirm, and reverse those records. In the conventional banking system, that authority is distributed among regulated institutions with defined roles. Banks manage customer accounts, central banks provide settlement assets and monetary infrastructure, payment networks transmit instructions, and legal systems determine how disputes and obligations are resolved. The system is digital, but its records are maintained through institutional trust.
Bitcoin changed this architecture. Its central problem was how a group of participants who do not necessarily trust one another could agree on a shared transaction history without appointing a bank, payment company, or other central operator to maintain the master ledger. This is difficult because digital information can be copied easily. A digital file can normally be duplicated without destroying the original, so a purely digital asset requires some way to prevent the same unit of value from being spent more than once. In conventional finance, trusted intermediaries solve this problem by checking their own records. Bitcoin proposed a different solution.
The Bitcoin network maintains a public ledger, commonly called the blockchain, that contains a history of transactions. Instead of being stored and controlled by a single institution, copies of this ledger are maintained by many independent computers participating in the network. These participants follow a common set of rules for determining which transactions are valid. A user can prove authority over bitcoin through cryptographic keys, while the network checks whether the coins being spent are actually available and whether the transaction follows the protocol's rules.
The blockchain itself is only part of the design. Bitcoin also needed a mechanism for deciding which valid transactions should become part of the accepted history when many participants are communicating over the internet and may disagree about the latest state of the ledger. It uses a process known as proof of work. Miners compete to add new blocks of transactions by performing computational work. The network then follows rules that allow participants to converge on a common history. Rewriting that history becomes increasingly difficult because doing so would require enormous computational effort relative to the honest network.
This arrangement reorganizes trust rather than eliminating it altogether. Bitcoin users do not need to trust a particular bank to maintain the ledger correctly, but they do rely on cryptography, software, network incentives, protocol rules, and a sufficiently decentralized group of participants. They must also protect their private keys or rely on a custodian that does so for them. The system replaces one kind of institutional dependence with a different combination of technical verification and economic incentives.
That distinction is important because discussions about Bitcoin often focus too heavily on the fact that it exists online. Digital payment systems were already widespread when Bitcoin was launched in 2009. Electronic banking had existed for decades, and earlier attempts at digital cash had also explored ways to transfer value electronically. What Bitcoin added was a practical method for creating a scarce digital asset whose ownership could be tracked on a shared network without requiring a central issuer to approve every transaction.
Scarcity is especially significant in a digital environment. Ordinary digital information is easy to reproduce. If someone sends a photograph by email, both the sender and the recipient can keep a copy. Money cannot work that way. If a person could copy a digital dollar and spend each copy independently, the accounting system would collapse. Traditional financial institutions prevent this by controlling their ledgers. Bitcoin prevents it through a publicly verifiable transaction history and rules that reject attempts to spend the same bitcoin twice.
This also changes the meaning of ownership. In a bank account, a customer's money is represented by a claim against a financial institution. Access to the balance depends on the bank's systems, identity procedures, legal framework, and operational policies. With Bitcoin held in a self-controlled wallet, the ability to authorize transactions depends primarily on possession of the relevant private keys. This gives users a form of direct control that resembles possession more closely than a conventional bank deposit does, although it creates a corresponding responsibility: losing the keys can mean losing access to the funds.
Bitcoin also separated the operation of the payment network from the issuance policy of the asset. In conventional monetary systems, central banks and commercial banks play important roles in the creation and management of money. Bitcoin instead follows rules encoded in its protocol that govern the issuance of new units and place a fixed upper limit on the total supply. Changes to those rules are not decided by a single executive or monetary authority. They depend on adoption by participants across the network, including developers, node operators, miners, businesses, and users.
That does not mean Bitcoin is free from governance. Every complex system has some form of governance, even when there is no central governing body. Developers propose software changes, miners choose what software to run, businesses decide which versions of the protocol they support, and users ultimately choose which network and rules they consider valuable. The difference is that authority is more dispersed and participation is based on shared protocol rules rather than a formal institutional hierarchy.
The contrast with banks should not be reduced to a simple argument that one system is good and the other is bad. Centralized financial systems offer advantages that decentralized systems often struggle to reproduce. Banks can reverse certain fraudulent transactions, recover accounts, extend credit, comply with court orders, provide customer service, and operate within legal frameworks that assign responsibility when something goes wrong. Bitcoin offers different properties, including open participation, predictable issuance rules, self-custody, and the ability to transfer value without requiring permission from a single central operator. Each architecture creates its own benefits, costs, and risks.
Understanding this distinction also clarifies why many later crypto projects focus on much more than creating new digital currencies. Once it became possible to maintain shared records without a single central database owner, developers began applying similar ideas to exchanges, lending systems, stablecoins, tokenized assets, digital identity, and other forms of financial infrastructure. The broader significance of blockchain technology comes from this question of coordination: can multiple parties share and update an authoritative record without relying on one organization to control it?
Bitcoin's historical importance therefore does not come from putting money on computers. Banks, card networks, and payment systems had already done that. Its breakthrough was to challenge the assumption that digital money required a central record keeper. Bitcoin showed that a network of independent participants could use cryptographic verification, shared rules, and economic incentives to maintain a common ledger and prevent double spending without appointing one institution as the final authority.
Seen this way, the difference between pre-Bitcoin digital money and Bitcoin is not mainly a difference in appearance. Both can be represented as numbers on a screen, transferred electronically, and stored without physical cash changing hands. The deeper distinction lies behind those numbers. Traditional digital money depends on institutions that control and reconcile private ledgers. Bitcoin created a system in which the ledger itself could be shared, independently verified, and maintained across a decentralized network. The innovation was not making money digital, but changing who gets to decide which digital records are valid.
