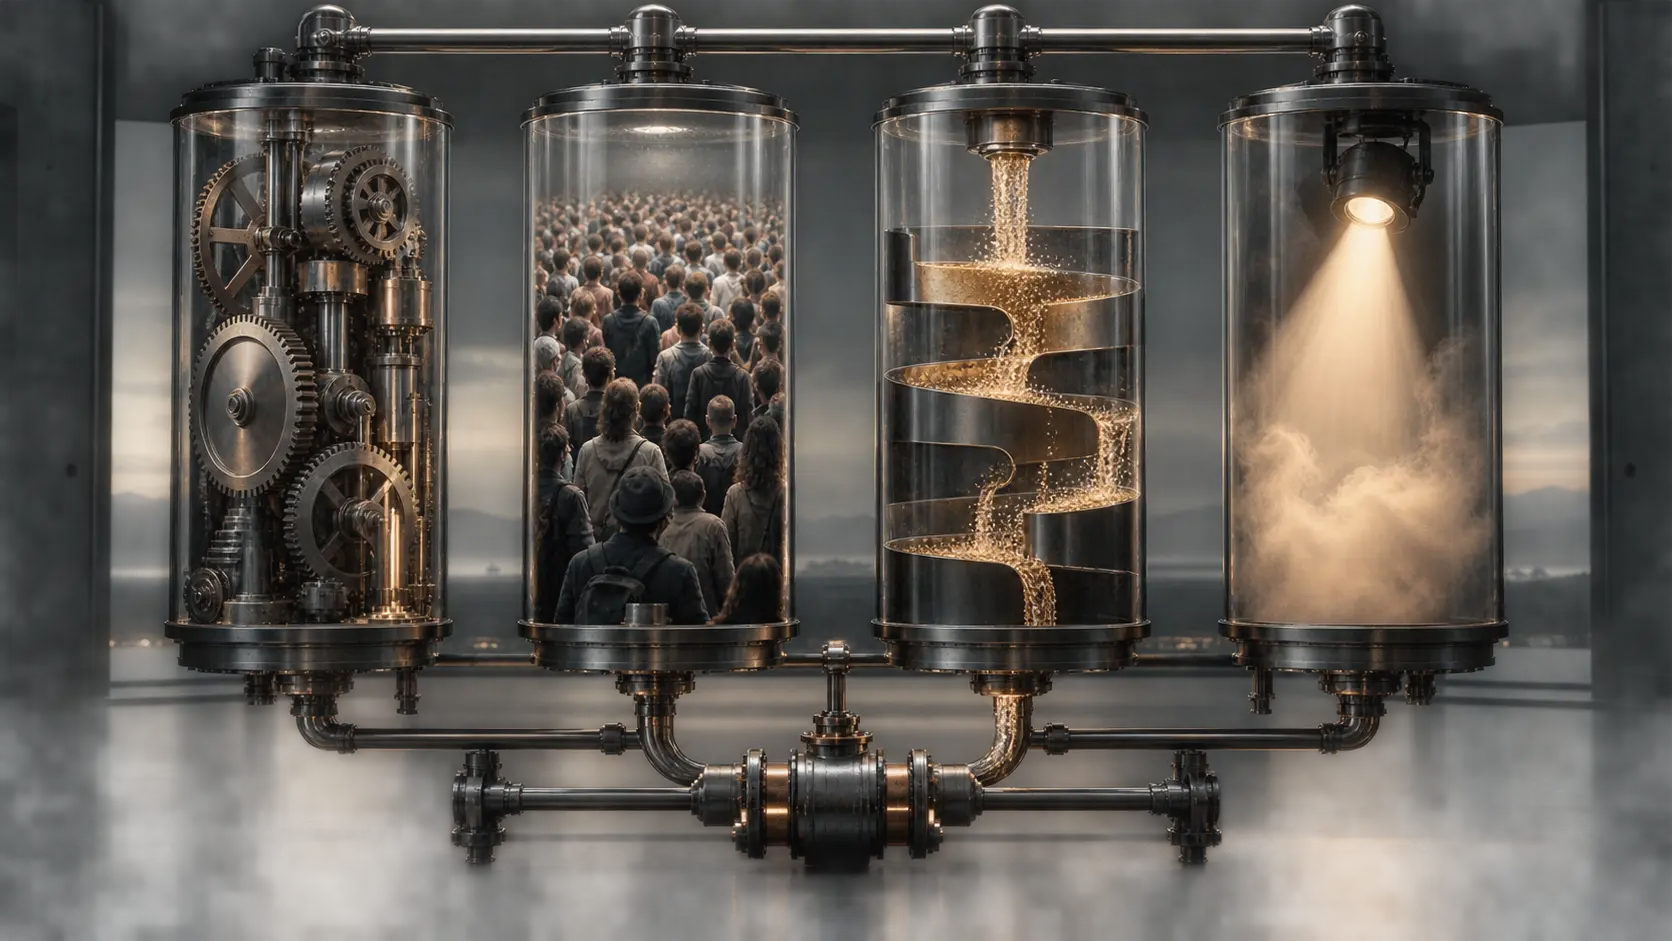
A crypto project can have impressive technology, growing usage, significant economic activity, and a powerful market narrative, yet these four elements do not necessarily move together. One of the most common analytical mistakes in crypto is to treat them as if they were different expressions of the same thing. They are not. A technically sophisticated network can have little adoption. A widely used protocol can generate little value for its token. A token can appreciate sharply because of a compelling narrative even when both adoption and economic activity remain limited. Understanding these differences makes it possible to evaluate projects without reducing the entire analysis to price.
Technology is the first layer. It concerns what the system can actually do and how well it does it. This includes matters such as security, scalability, transaction speed, privacy, programmability, decentralization, reliability, interoperability, and the quality of the tools available to developers. A technological improvement can be meaningful even if few people are using it yet. A blockchain may solve a real technical problem or introduce an elegant architecture before there is meaningful demand for the product.
Technical quality, however, does not guarantee adoption. Many technologies fail to become widely used despite being well designed, while less sophisticated alternatives sometimes dominate because they are easier to access, better distributed, more familiar, or supported by stronger ecosystems. Adoption is therefore a separate layer. It asks whether people, developers, businesses, or institutions are actually using the system and whether that use persists over time.
Adoption should also be examined carefully because not all activity represents the same thing. A network can show high transaction counts because of automated trading, temporary incentives, token farming, or speculative campaigns. That is still activity, but it may not represent durable demand. More meaningful adoption usually appears when users continue to return after incentives decline, developers keep building, applications retain users, and the network solves a problem well enough that people prefer it over alternatives.
The distinction between technology and adoption can be summarized simply: technology describes capability, while adoption describes behavior. A system can be capable of serving millions of users without actually attracting them. Conversely, a system with technical limitations can still achieve substantial adoption because it benefits from liquidity, brand recognition, existing infrastructure, or network effects. Evaluating one dimension does not eliminate the need to examine the other.
Economic value forms a third layer. It concerns what useful economic activity the system creates, coordinates, or captures. This can include fees paid for transactions, revenues earned by applications, demand for block space, financial services delivered through a protocol, or other activity for which participants are willing to pay. Economic value is not simply the amount of money flowing through a network. Large volumes can be generated by repetitive or subsidized activity without creating much sustainable value.
More importantly, economic value generated by a network is not automatically captured by its token. This is one of the most important distinctions in crypto analysis. A blockchain can become highly useful while its token captures only a small part of the benefits. The opposite can also occur temporarily: a token can achieve a very high valuation even though the underlying network generates little economic activity.
Value capture depends on the design of the asset. Analysts need to ask why the token exists and what creates demand for it. It may be required to pay transaction fees, provide security through staking, serve as collateral, grant governance rights, or provide access to some feature. Supply also matters. If new tokens are issued rapidly, growing demand may be offset by dilution. If fees are distributed to participants, burned, or retained elsewhere in the system, the consequences for token holders can differ substantially.
This means that the chain from technological success to token appreciation contains several separate steps. Better technology may support greater adoption. Greater adoption may create more economic activity. More economic activity may increase demand for some scarce resource in the system. Only then might that demand translate into stronger economics for the token. Every connection in this chain needs to be examined rather than assumed.
Narrative is the fourth layer, and it behaves differently from the other three. A narrative is the collective story that explains why a project matters and why it could become more valuable in the future. Narratives can be built around technological breakthroughs, future adoption, institutional interest, artificial intelligence, tokenization, gaming, privacy, decentralized finance, or almost any other theme that captures market attention.
Narratives are not inherently misleading. A strong narrative may describe a genuine technological transition before adoption becomes visible. Markets are forward-looking, so investors naturally try to anticipate future developments. The problem begins when the story is treated as evidence that the future has already arrived. A project can be associated with a promising trend without having demonstrated that it can capture a meaningful share of that trend.
Narrative also moves much faster than the other layers. A new idea can become popular within days. Token prices can reprice within hours. Technological development and user adoption usually move far more slowly. Economic value may take even longer to establish because sustainable markets require users, infrastructure, competition, and repeatable demand. This difference in speed creates many of the largest gaps between price and reality in crypto.
A useful conceptual model is therefore to evaluate a project through four independent questions. First, does the technology provide a real and defensible capability? Second, is anyone actually adopting it in a durable way? Third, does that adoption produce economic value, and how much of that value can the token capture? Fourth, what expectations are already embedded in the narrative and market valuation?
These questions should be answered separately before they are connected. Starting with price can distort the analysis because strong price performance creates a temptation to search for explanations that justify the result. A better approach is to work from the underlying system outward. Begin with what the technology does, then examine who uses it, then determine where economic value appears, and only after that compare those fundamentals with the market's expectations.
Consider a hypothetical blockchain that can process transactions cheaply and quickly. That is a technological characteristic. If developers begin building applications on it and users interact with those applications regularly, adoption is emerging. If those activities produce persistent demand for block space and meaningful fees, economic value is being created. If the token is required to pay those fees or secure the network, some of that value may support demand for the asset. But if the token already trades at a valuation that assumes enormous global adoption, the narrative may have advanced much farther than the evidence.
The reverse situation is also possible. A technically unremarkable network may have substantial adoption because it has deep liquidity, mature applications, strong developer communities, and years of accumulated infrastructure. Its importance cannot be dismissed merely because a newer competitor has better specifications. Technology is only one input into economic success.
This framework also helps explain why comparisons based solely on token price can be misleading. Price combines current conditions with expectations about the future. It can reflect real adoption, expected adoption, liquidity conditions, speculative demand, leverage, market sentiment, and the relative scarcity of the asset. A rising price therefore does not reveal which of these forces is responsible.
The same caution applies to market capitalization. A large market value does not automatically indicate proportionally large economic output, just as a small market value does not prove that a technology lacks usefulness. Market capitalization is a valuation produced by the market. It is not a direct measurement of technical quality, users, revenues, or social importance.
A more complete analysis therefore resembles a chain rather than a single score. Technology creates possible capabilities. Adoption reveals whether people find those capabilities useful. Economic activity shows whether the use creates something participants are willing to pay for. Token design determines whether the asset captures part of that value. Narrative influences how far ahead of current reality investors are willing to price the future.
Weak projects can fail at any point in this chain. Some have interesting technology but no users. Others attract users through temporary incentives but generate little sustainable economic value. Some produce meaningful activity while their token has weak mechanisms for capturing that value. Others may have credible technology, adoption, and economics but still become poor investments because the market price already assumes an unrealistically successful future.
Strong analysis therefore requires resisting the temptation to compress everything into one judgment. A project can deserve credit for technical innovation without deserving a high token valuation. It can have substantial adoption without possessing strong token economics. It can generate meaningful fees while still facing competitive risks. It can also be surrounded by exaggerated speculation while continuing to make legitimate technological progress.
Separating technology, adoption, economic value, and narrative does not eliminate uncertainty, but it makes uncertainty easier to locate. Instead of asking whether a project is simply “good” or whether its token will rise, the analyst can identify which parts of the thesis are demonstrated, which are developing, and which remain assumptions about the future. That distinction is especially valuable in crypto, where price often moves faster than the underlying systems it is supposed to represent.
