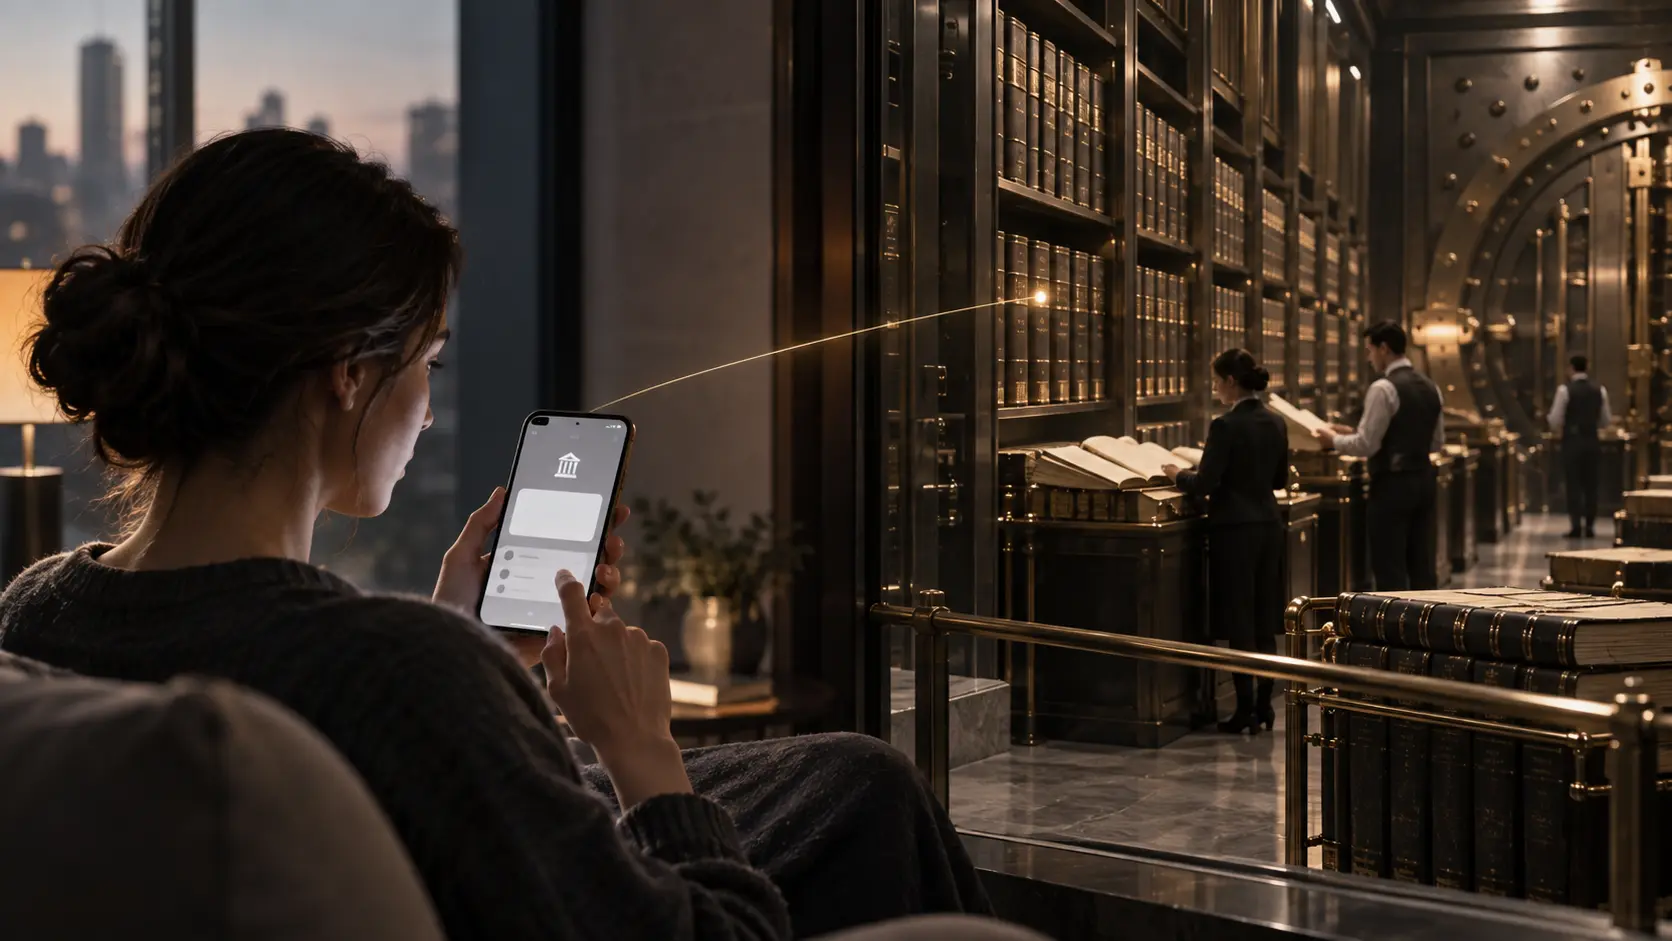
When you open a banking app and see a balance of $5,000, it is natural to think of that number as the money itself. In practice, the number is only a representation of a claim recorded inside a financial system. What makes the balance meaningful is not the screen displaying it, but the fact that banks, payment networks, clearing systems, courts, regulators, and other institutions recognize the underlying records. Digital money works because a network of trusted systems agrees on who owns what, which transactions are valid, and when balances should change.
This becomes easier to understand by comparing a bank balance with physical cash. If you hold a $20 note, possession of the note is an important part of what gives you control over it. With money in a bank account, there is usually no specific collection of banknotes stored in a vault under your name. Instead, the bank records that it owes you a certain amount. Your balance is an accounting entry within a larger system of assets, liabilities, payments, and legal obligations. When you spend money, the system updates those records rather than moving a pile of physical currency that has been reserved exclusively for you.
A digital balance therefore depends on an authoritative ledger. A ledger is simply a record of who owns, owes, or has transferred value. Banks maintain ledgers for their customers, while financial institutions also keep accounts with one another and use larger settlement systems to complete payments across the economy. If you send money to another customer at the same bank, the bank can often make the change internally by reducing one account and increasing another. If the recipient uses a different bank, additional institutions and settlement mechanisms may become involved.
The number shown in your app is the visible end of this process, not the process itself. Behind a simple payment may be authorization checks, fraud controls, payment messages, clearing arrangements, settlement obligations, and reconciliation between multiple institutions. A debit card purchase can appear almost instantly even though the final transfer of funds between the relevant parties may occur through a more complicated sequence. What matters is that the institutions involved eventually agree on the records.
This is why a screenshot of a bank balance has almost no financial authority by itself. Anyone could alter an image to display a different number, but changing pixels does not change the bank's ledger. The same is true of a spreadsheet created on a personal computer. You can type "$1 million" into a cell, but the number does not become money because no recognized financial system accepts it as proof that you possess $1 million. A digital number becomes economically meaningful only when it is connected to a system capable of establishing ownership and honoring transactions.
The idea of recognition is central. Suppose a technical error causes your banking app to display $100,000 when the bank's actual records show $1,000. The larger figure would not normally give you a legitimate claim to the extra money simply because it appeared on your screen. The institution's underlying records, transaction history, contractual obligations, and applicable law would determine the correct balance. The interface is a window into the accounting system, not the final authority over it.
The same principle becomes clearer when payments are disputed. A customer may believe a transaction was unauthorized, a merchant may claim that payment was completed, and a bank may have records showing exactly when and how the transaction occurred. Resolving the disagreement requires more than looking at the balance currently displayed. Institutions may review authorization data, account histories, payment rules, and legal protections. In other words, money is not merely a number. It is a number embedded in a system of recognized rights and obligations.
This does not mean a single bank determines all financial reality. Modern money depends on several layers of institutions. Commercial banks maintain customer accounts, payment networks help transmit instructions, clearing systems calculate obligations between participants, and central banks often provide the final settlement asset used between financial institutions. Regulators and legal systems define many of the rules governing deposits, ownership, insolvency, fraud, and disputes. The answer to the question of who decides how much money you have is therefore usually not one person or one organization, but an interconnected institutional structure.
Different forms of money also involve different kinds of claims. Cash issued by a central bank is not the same thing as a commercial bank deposit, even though both may be denominated in the same currency. A bank deposit generally represents a claim on the bank. Electronic money issued by a payment company may depend on another legal structure. A balance held through an investment platform may represent cash, securities, or claims on a custodian. Two applications can display the same currency symbol while the legal and financial meaning of the balances behind them is different.
This distinction becomes especially important during financial stress. If an institution becomes insolvent or loses access to its payment systems, customers may discover that a visible balance and the immediate ability to use that balance are not identical. Deposit insurance, bankruptcy rules, custody arrangements, and the institution's financial position can suddenly matter a great deal. In ordinary times, these layers remain largely invisible because the system works smoothly. Problems reveal how much a digital balance depends on the institutions that stand behind it.
Money also depends on identity. A financial institution does not merely record that "$3,000 exists." It records that a particular account has a claim to that amount, and it maintains rules for determining who is authorized to control the account. Passwords, identity checks, signatures, payment credentials, and fraud systems connect a person or organization to the relevant records. If someone steals your banking password, the underlying money does not automatically become theirs in a legal sense, even though they may temporarily gain the technical ability to initiate transactions. Ownership, authorization, and access are related concepts, but they are not always identical.
Cryptocurrencies make this distinction visible in a different way. On a blockchain such as Bitcoin, ownership is not recorded by a bank in a private customer database. Instead, the network maintains a shared transaction history and applies common rules to determine which units can be spent. Control is demonstrated through cryptographic keys rather than through a conventional account administrator. No bank employee needs to approve an ordinary Bitcoin transfer, but the transaction still depends on a recognized record system. The difference is that the system of recognition is organized around software rules and distributed verification rather than a central account keeper.
This shows that even decentralized digital money cannot escape the need for records. Bitcoin did not make ledgers unnecessary; it created a different way to maintain one. The network still needs to determine which transactions are valid, whether a unit has already been spent, and which history participants accept as authoritative. Without agreement about those records, the numbers associated with cryptocurrency addresses would be no more meaningful than numbers entered into an arbitrary database.
Stablecoins provide another useful example because they often combine blockchain records with traditional financial institutions. A dollar-linked stablecoin may circulate as a token on a blockchain, while the issuer holds reserves in banks or financial instruments. The blockchain can show how many tokens a particular wallet controls, but the economic value of those tokens may also depend on the issuer's reserves, redemption policies, legal structure, and access to the banking system. The visible digital token is therefore part of a larger chain of recognized claims.
The same principle applies to tokenized financial assets. A digital token might claim to represent a bond, a share in a fund, or an interest in another asset. The blockchain can record possession of the token, but that record becomes financially meaningful only if the legal and institutional system recognizes what the token represents. A token that supposedly represents ownership of a building, for example, does not automatically override property law or official land records. Digital representation and legally recognized ownership must be connected.
This is why discussions about digital money often become debates about trust. Traditional systems ask users to trust institutions, legal rules, auditors, payment infrastructure, and operational controls. Decentralized systems try to reduce dependence on particular institutions by replacing some forms of trust with transparent rules, cryptographic verification, and distributed networks. Neither approach eliminates the need for a mechanism that determines which records count. They simply organize that mechanism differently.
It is also why money can become temporarily inaccessible without ceasing to appear on a screen. A bank may freeze an account because of a legal order or suspected fraud. A payment service may limit withdrawals. A blockchain user may lose a private key while the associated balance remains permanently visible on the public ledger. In each case, the recorded value may continue to exist while the person's practical ability to use it changes. Possession, legal ownership, technical access, and spendability can therefore diverge.
The deeper lesson is that modern money is not simply information, even though it is increasingly represented as information. It is information supported by rules about authority, ownership, settlement, and recognition. A balance matters because a system accepts that record and allows it to be used to settle obligations, purchase goods, repay debts, or transfer value to someone else. The number on the screen is only the most convenient way to display that relationship.
So who decides how much money you really have? In a traditional financial system, the answer emerges from the records and rules maintained by banks, payment systems, central banks, and legal institutions. In a cryptocurrency network, it emerges from a shared ledger and the protocol rules accepted by its participants. In either case, money depends on more than a displayed number. What counts is whether a recognized system agrees that the value belongs to you and whether that system will honor your attempt to use it.
