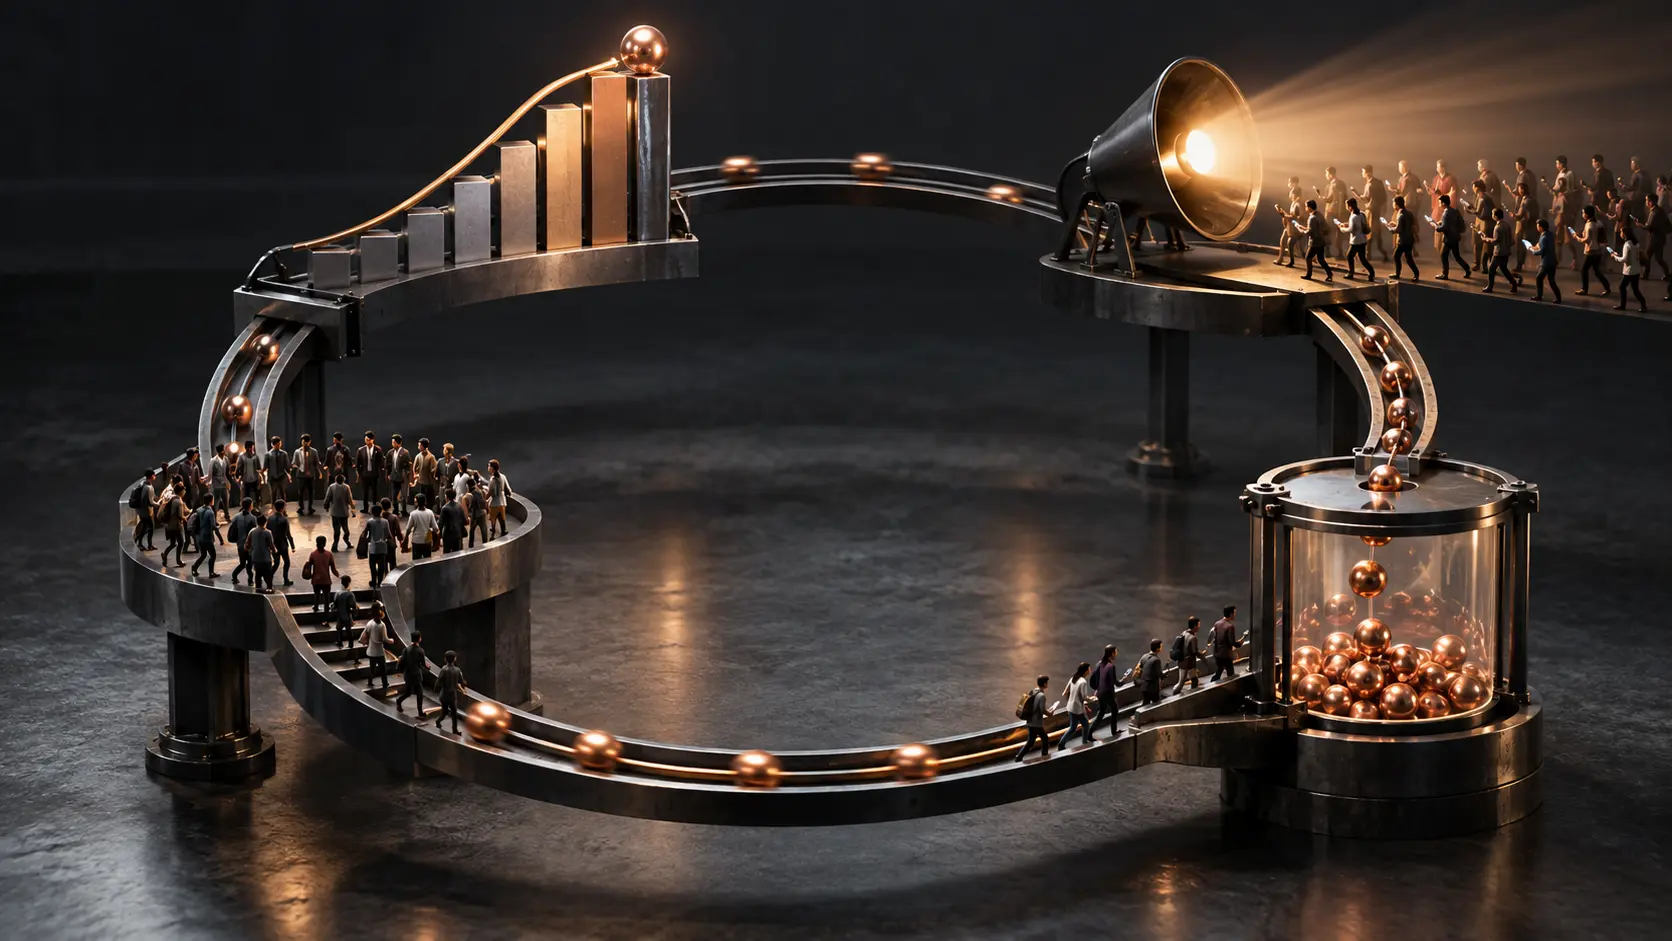
Crypto markets often move in waves that seem larger than the original events that started them. A modest rise in price can develop into a broad period of optimism, growing participation, and speculation, while a decline can trigger the opposite process and deepen into a prolonged contraction. This happens because crypto prices do not move independently from attention, capital, network activity, and investor expectations. Each of these factors can influence the others, creating feedback loops that make both booms and downturns partly self-reinforcing.
The upward cycle usually begins with price appreciation. The initial cause can vary: improving economic conditions, a technological development, greater institutional interest, a regulatory change, or simply the exhaustion of a previous period of selling. Whatever the trigger, rising prices immediately change how the market is perceived. Investors who had ignored crypto begin paying attention again, financial media increase their coverage, social networks become more active, and past success stories return to public discussion. Price is therefore not only an outcome of demand. In crypto markets, it is also one of the strongest forms of advertising.
Greater attention brings new buyers. Some are long-term investors who believe valuations have become attractive, while others enter because they see prices rising and expect the movement to continue. Existing holders may also become more willing to increase their positions as their confidence improves. This additional demand pushes prices higher, apparently confirming the idea that the market has entered a new expansion. The higher prices go, the easier it becomes for participants to interpret previous optimism as justified rather than speculative.
Rising prices also increase the wealth of people who already own crypto assets. Because their portfolios are now worth more, they have more capital available to reinvest. Profits from established assets such as Bitcoin or Ethereum may flow into smaller tokens, decentralized finance projects, new blockchains, digital collectibles, or other speculative areas. This movement spreads the boom through the wider ecosystem. A rally that began in a small part of the market can gradually become a broad expansion in which many assets rise together.
Higher valuations also improve conditions for crypto companies and developers. Projects can raise money more easily when investors are optimistic and token prices are strong. Venture capital becomes more willing to fund startups, exchanges see larger trading volumes, and developers may be attracted by the prospect of greater funding and user interest. New products are launched, more tokens are created, and marketing activity increases. Some of this expansion can produce genuine innovation, but some of it exists mainly because abundant capital makes experimentation and speculation easier.
Network activity often rises at the same time. More people open accounts, trade assets, use decentralized applications, borrow and lend tokens, or participate in new protocols. This increased activity can create the appearance of stronger fundamental demand. In some cases, the improvement is real: more users can make a network more useful, attract developers, and strengthen its economic ecosystem. In other cases, activity is heavily driven by speculation and may disappear quickly when prices stop rising. During a strong bull market, however, it can be difficult to distinguish durable adoption from activity created by the boom itself.
Expectations are central to this process. Investors do not buy only because conditions are good today; they often buy because they expect conditions to become even better tomorrow. If a rising market attracts new users, capital, companies, and media coverage, participants may conclude that future demand will also increase. That expectation encourages additional buying in the present. In this way, anticipated future growth can help produce the growth that investors expect, at least for a time.
Leverage can make the cycle even more powerful. Traders may borrow money or use derivatives to increase their exposure when they believe prices will continue rising. As the market moves upward, profitable positions can support further risk-taking. Traders feel wealthier, lenders become more comfortable extending credit, and collateral values increase. More leverage then enters the system, amplifying demand. This mechanism can accelerate a bull market, but it also makes the eventual reversal more dangerous because borrowed positions must remain adequately collateralized.
The cycle cannot reinforce itself indefinitely. As prices rise, valuations may eventually become difficult to justify even under optimistic assumptions. New investors may enter mainly because they expect to sell to someone else at a higher price rather than because they believe the asset's underlying use has improved. Speculation becomes more aggressive, leverage increases, and weaker projects can attract capital simply because risk appetite is high. The market becomes dependent on a continued supply of new money and continued confidence.
A reversal can begin for many reasons. Interest rates may rise, liquidity may tighten, a major company or project may fail, regulation may become more restrictive, or investors may simply decide that prices have moved too far. The specific trigger is often less important than the structure that exists when the decline begins. A highly leveraged and extremely optimistic market can be vulnerable even to a relatively modest disappointment.
Once prices fall, the same forces that strengthened the boom begin operating in reverse. Losses reduce investor wealth and confidence. Traders become less willing to take risks, while potential new participants see negative headlines instead of stories about rapid gains. Media attention often becomes focused on bankruptcies, fraud, liquidations, and failed projects. Interest declines, trading volumes fall, and the flow of new capital weakens. Falling prices therefore discourage the very demand that could help stabilize them.
Leverage makes this downward process especially severe. When collateral loses value, leveraged traders may be forced to sell assets to repay loans or meet margin requirements. Those forced sales push prices lower, which can trigger additional liquidations. The result is another feedback loop: falling prices create selling, and selling causes further declines. Crypto markets have repeatedly experienced periods in which liquidations magnified movements that had initially begun for unrelated reasons.
The decline in prices also affects the broader industry. Lower token values reduce the resources available to projects whose treasuries are held partly in crypto assets. Venture funding becomes harder to obtain, trading revenues fall, startups reduce hiring, and less successful projects disappear. Developers and entrepreneurs may shift toward other industries or wait for better conditions. With fewer new launches and less public excitement, user activity can fall further, weakening the narrative that previously supported high valuations.
Psychology reinforces the contraction. During a boom, investors may interpret almost every development positively. During a downturn, the same market can become unusually skeptical. A new product that would have generated excitement during a bull market may attract little interest in a bear market. Investors who once feared missing future gains may instead fear further losses. Because expectations have changed, the same information can produce a very different market reaction.
This helps explain why crypto cycles can feel disconnected from changes in underlying technology. A blockchain may continue processing transactions and developers may continue improving its software even while its token loses most of its market value. Conversely, an asset can appreciate rapidly without an equivalent increase in practical use. Prices, adoption, and technological progress influence one another, but they do not always move at the same speed. Financial feedback loops can temporarily dominate slower fundamental developments.
The self-reinforcing nature of crypto markets is particularly strong because the sector combines several characteristics rarely found together elsewhere. Trading occurs continuously, many assets are highly volatile, leverage is widely available, global participation is easy, and public discussion spreads instantly through social media. Many tokens also lack widely accepted valuation methods, making expectations about future adoption especially important. When investors cannot anchor prices easily to earnings, cash flows, or other traditional measures, market sentiment can have greater influence.
None of this means that crypto cycles are entirely irrational. Rising prices can genuinely finance development, attract talent, improve liquidity, and introduce new users to useful technologies. Falling prices can remove weak projects, reduce excessive leverage, and force surviving businesses to become more efficient. The important distinction is that fundamental progress and market reflexivity can occur at the same time. Real improvements can start a rally, and the rally can then create additional economic activity that would not have existed without the rising prices.
Crypto cycles therefore feed on themselves because price, attention, capital, activity, and expectations are tightly connected. Appreciation attracts interest and money, which can generate more usage and further appreciation. Declines reduce wealth and confidence, trigger selling, weaken activity, and make additional declines more likely. These feedback loops do not determine where every cycle will begin or end, but they help explain why crypto markets often move much farther in both directions than the original catalyst alone would suggest.
